Centurion Corporation Limited S$200mn 4% 5-Year Sustainability Notes: Credit View

Tan Tze Yi / Fixed Income Analyst / +6018-6951688

 |   07 Oct 2026  |    14 views

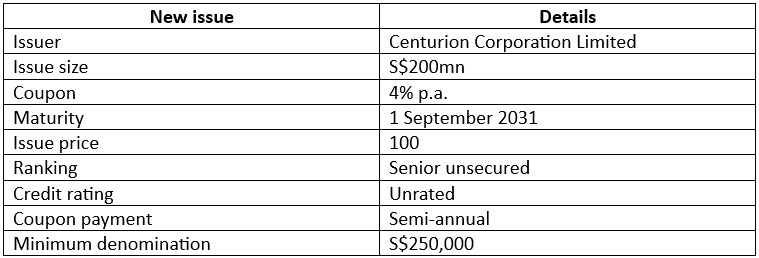
Centurion Corporation Limited (CCL) issued S$200mn of 4% senior unsecured sustainability notes due 1 September 2031 on 1 September 2026. The notes were issued at par, paid interest semi-annually and had a minimum denomination of S$250,000. The transaction was oversubscribed and upsized, making it Centurion’s largest and longest-dated bond issuance to date.

FactsheetsSource: Bloomberg

The net proceeds are earmarked to finance or refinance eligible green and social projects under CCL’s Sustainability Financing Framework.


1H26 Credit Performance Highlights

Stronger operating earnings improved debt-servicing capacity.
Revenue rose 31% YoY to S$184.9mn, driven by the consolidation of Westlite Mandai, new beds at Westlite Toh Guan and Westlite Mandai, and contributions from EPIISOD Macquarie Park and the Harum Megah portfolio. Adjusted EBIT (excludes property fair-value movements) increased 28% YoY to S$118.3mn from S$92.6mn, outpacing the increase in finance costs and improving adjusted EBIT/finance cost coverage to 5.2x from 4.7x (company-reported ICR: 5.6x). Occupancy remained healthy at 94% for Singapore PBWA (CCL’s core market), and 98% for UK PBSA, supporting recurring rental earnings.

Near-term liquidity remains adequate, although asset encumbrance is high.
CCL had S$301.7mn of cash against S$37.5mn of borrowings due within one year. Of the Group’s S$1.08bn borrowings, S$657.7mn was held within CAREIT, while non-REIT entities had S$418.2mn of borrowings and S$279.7mn of cash. This suggests that consolidated leverage overstates the debt carried outside CAREIT, although not all non-REIT cash may be readily available to service the parent’s unsecured bonds. Asset encumbrance also remains high, with c.S$2.88bn (92%, of investment properties pledged), limiting the pool of unpledged assets available to unsecured creditors.

Leverage increased with portfolio expansion.
Net gearing rose to 24% from 12% at FY25 as borrowings increased to S$1.08bn, mainly to fund property acquisitions and development. Investment outflows of S$446.9mn exceeded OCF of S$104.7mn, increasing in greater reliance on external funding. Hence, leverage is likely to remain elevated in the near term as earnings from the new capacity have yet to fully ramp up.


Post 1H26 Credit Performance Highlights

Expansion supports future earnings, but keeps funding needs elevated.
CCL secured the c.7,000-bed Kranji Close PBWA site in August and subsequently expanded its Singapore PBWA development pipeline further. Separately, the Group agreed to acquire a 7,974-bed PBWA asset in Pasir Gudang for RM214.5mn (c.S$67.2mn), increasing its Malaysian bed capacity by 22% to c.43,980 beds. While these investments expand CCL’s recurring earnings base, they come at a time when leverage has already increased following significant investment in 1H26. With further development and acquisition spending ahead, we expect leverage and external funding needs to remain elevated until the new capacity ramps up and contributes more meaningfully to cash flow.


Outlook

Outlook remains positive, with earnings expected to strengthen as new capacity ramps up.
Management expects Singapore occupancy to improve in 2H26 as new beds at Westlite Toh Guan and Westlite Mandai filled progressively. This should support further earnings growth, with management guiding for c.22% YoY revenue growth in 2H26 to c.S$190mn. Singapore PBWA demand remains firm, underpinned by S$47–53bn of expected construction demand and a 5.6% increase in CMP work permit holders.


Relative Value
FactsheetsSource: Bloomberg

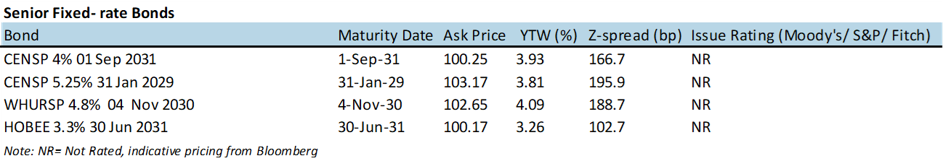
The Centurion 2031 currently trades at 3.93% YTW and 167bps Z-spread. Compared with Centurion 2029, investors receive only 12bps more yield for around 2.6 additional years of tenor, while the Z-spread is 29bps tighter. We think the tighter spread partly reflects stronger demand and better liquidity for the larger S$200mn 2031 issue. As such, the 2029 offers better spread compensation, although investors may have to accept lower liquidity.

Compared with Wee Hur 2030, the closest operating peer, Centurion 2031 offers 16bps less yield and trades 22bps tighter, suggesting that Centurion’s stronger credit profile is already reflected in its pricing. At the other end, Ho Bee 2031 trades around 64bps tighter, consistent with its stronger credit profile.

Overall, we see Centurion 2031 as fairly valued. It offers a reasonable yield for investors seeking Centurion exposure. Within Centurion’s own curve, the 2029 offers higher credit-spread compensation despite its shorter maturity, although part of the wider spread likely reflects lower liquidity.


Our Credit View

We remain positive on CCL’s credit profile. We think the increase in leverage is currently supported by stronger operating earnings, 5.2x interest coverage and adequate near-term liquidity. Firm Singapore PBWA demand should support the ramp-up of new capacity, with management guiding for c.22% YoY revenue growth in 2H26, further providing further support for debt-servicing capacity.


Company Overview:

Centurion Corporation Limited (CCL) is a Singapore-listed accommodation owner and operator, with a portfolio of 85,528 beds across Singapore, Malaysia, the UK, Australia and China. Its core businesses comprise Purpose-Built Workers Accommodation (PBWA) and Purpose-Built Student Accommodation (PBSA). PBWA is the main earnings contributor, accounting for 77% of 1H26 revenue, with Singapore as CCL’s largest market.
Related Articles

Aspial Lifestyle Priced S$75mn 5.00% 5-Year SGD Bond: Credit View

Aspial Lifestyle priced S$75mn of 5.00% senior unsecured notes due 6 October 2031 on 24 September 2026.

 |   02 Oct 2026

The bond market has bought the Fed time

When the Federal Reserve left interest rates unchanged at 3.50%–3.75% at its July meeting, the decision came as little surprise. Markets had largely expected the Committees to remain on hold.

 |   30 Jul 2026

Clifford Capital’s Bayfront Infrastructure Asset-Backed Securities (IABS) Platform

Clifford Capital is an infrastructure credit platform specialising in global infrastructure debt origination, distribution and investment, founded in 2012 and headquartered in Singapore.

 |   21 Jul 2026

Disclaimers


These commentaries are intended for general circulation. It does not have regard to the specific investment objectives, financial situation and particular needs of any person who may receive this document. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of the units and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. Investors may wish to seek advice from a financial adviser before investing. In the event that investors choose not to seek advice from a financial adviser, they should consider whether the investment is suitable for them.

The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the "Research") contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.

Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.

IMPORTANT INFORMATION

This material is provided by Phillip Capital Management (S) Ltd (“PCM”) for general information only and does not constitute a recommendation, an offer to sell, or a solicitation of any offer to invest in any of the exchange-traded fund (“ETF”) or the unit trust (“Products”) mentioned herein. It does not have any regard to your specific investment objectives, financial situation and any of your particular needs. You should read the Prospectus and the accompanying Product Highlights Sheet (“PHS”) for key features, key risks and other important information of the Products and obtain advice from a financial adviser (“FA“) pursuant to a separate engagement before making a commitment to invest in the Products. In the event that you choose not to obtain advice from a FA, you should assess whether the Products are suitable for you before proceeding to invest. A copy of the Prospectus and PHS are available from PCM, any of its Participating Dealers (“PDs“) for the ETF, or any of its authorised distributors for the unit trust managed by PCM.  

An ETF is not like a typical unit trust as the units of the ETF (the “Units“) are to be listed and traded like any share on the Singapore Exchange Securities Trading Limited (“SGX-ST”). Listing on the SGX-ST does not guarantee a liquid market for the Units which may be traded at prices above or below its NAV or may be suspended or delisted. Investors may buy or sell the Units on SGX-ST when it is listed. Investors cannot create or redeem Units directly with PCM and have no rights to request PCM to redeem or purchase their Units. Creation and redemption of Units are through PDs if investors are clients of the PDs, who have no obligation to agree to create or redeem Units on behalf of any investor and may impose terms and conditions in connection with such creation or redemption orders. Please refer to the Prospectus of the ETF for more details.  

Investments are subject to investment risks including the possible loss of the principal amount invested. The purchase of a unit in a fund is not the same as placing your money on deposit with a bank or deposit-taking company. There is no guarantee as to the amount of capital invested or return received. The value of the units and the income accruing to the units may fall or rise. Past performance is not necessarily indicative of the future or likely performance of the Products. There can be no assurance that investment objectives will be achieved.  

Where applicable, fund(s) may invest in financial derivatives and/or participate in securities lending and repurchase transactions for the purpose of hedging and/or efficient portfolio management, subject to the relevant regulatory requirements. PCM reserves the discretion to determine if currency exposure should be hedged actively, passively or not at all, in the best interest of the Products.  

The regular dividend distributions, out of either income and/or capital, are not guaranteed and subject to PCM’s discretion. Past payout yields and payments do not represent future payout yields and payments. Such dividend distributions will reduce the available capital for reinvestment and may result in an immediate decrease in the net asset value (“NAV”) of the Products. Please refer to <www.phillipfunds.com> for more information in relation to the dividend distributions.  

The information provided herein may be obtained or compiled from public and/or third party sources that PCM has no reason to believe are unreliable. Any opinion or view herein is an expression of belief of the individual author or the indicated source (as applicable) only. PCM makes no representation or warranty that such information is accurate, complete, verified or should be relied upon as such. The information does not constitute, and should not be used as a substitute for tax, legal or investment advice.  

The information herein are not for any person in any jurisdiction or country where such distribution or availability for use would contravene any applicable law or regulation or would subject PCM to any registration or licensing requirement in such jurisdiction or country. The Products is not offered to U.S. Persons. PhillipCapital Group of Companies, including PCM, their affiliates and/or their officers, directors and/or employees may own or have positions in the Products. Any member of the PhillipCapital Group of Companies may have acted upon or used the information, analyses and opinions herein before they have been published. 

This advertisement has not been reviewed by the Monetary Authority of Singapore.  


Phillip Capital Management (S) Ltd (Co. Reg. No. 199905233W)  
250 North Bridge Road #06-00, Raffles City Tower ,Singapore 179101 
Tel: (65) 6230 8133 Fax: (65) 65383066 www.phillipfunds.com

?>