Halyk Bank: Balancing Yield And Growth November 11, 2026
Investment Overview
Kazakhstan’s largest bank by assets, Halyk Bank (KASE: HSBK), offers an attractive dividend yield, but slowing earnings growth and rising credit risks raise questions about the sustainability of future payouts.
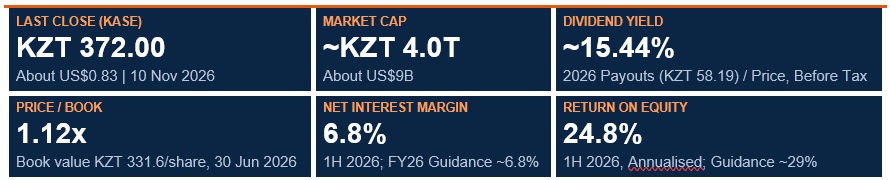
Price/book compares the share price with the bank’s net worth per share. Net interest margin is what the bank keeps from lending after paying for deposits. Return on equity is the profit earned on shareholders’ money.
Still Earning Over KZT 200 Billion A Quarter, After A Record 2025
Quarterly Net Income, KZT Billion
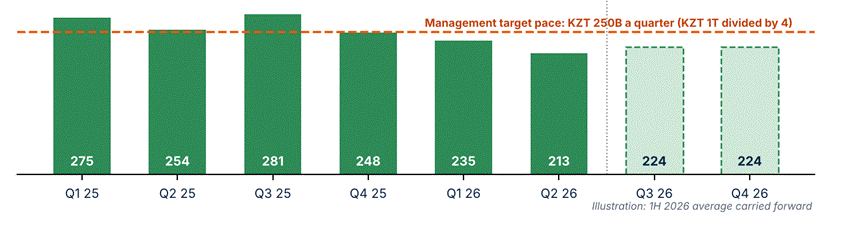
Q1 2025 to Q2 2026 are actual results. The Q3 and Q4 2026 bars are an illustration, not an analyst forecast. The orange line is management’s ~KZT 1 trillion target for 2026 spread evenly across four quarters.
Source: JSC Halyk Bank, Interim Condensed Consolidated Financial Information for the Six Months Ended 30 June 2026 (Unaudited).
| Why It Is Interesting• Number one in Kazakhstan by assets, loans, deposits and net income (40.2% of sector profit in Q2).• High dividend: 2026 payouts of KZT 58.19 per share represent approximately 15.7% of the price, and about 60% of 2025 profit was distributed.• Strong capital cushion: 19.0% core capital ratio vs a 9.5% minimum, though it fell from 21.0% in March after dividend payments.• Lending recovered in Q2 (net loans +4.0% on the quarter), and the stock trades near 1.1x book.• Growing economy: Kazakhstan’s GDP rose 4.2% in January-September 2026, led by non-resource sectors, and system-wide loans are up about 14% and deposits 17% on a year ago.• Large customer base: 8.6 million monthly super-app users, and active Halyk salary cards equal about 39% of Kazakhstan’s employed population. | Be Careful• Profit is falling: 1H net income down 15.3%, and Q2 was the lowest in two years.• Regulation is squeezing margins: higher central-bank reserve requirements cut the net interest margin to 6.8% from 7.3%, and tighter retail-lending rules have hurt fees.• Bad loans are rising: loans overdue by more than 90+ days increased to 5.3% of total loans (up from 4.3% at year-end, 3.0% a year ago), and loan-loss charges rose 69%.• The yield looks high partly because 2025 was a record profit year.• Trading is thin, and a controlling shareholder holds most of the stock. |
| Who It May Suit: Dividend-seeking investors who are comfortable with frontier market risks, including profit volatility, share price swings, and lower liquidity. If you hold it, keep it to a small slice of your portfolio. |
Halyk Bank: The Details
What It Does
Halyk is the country’s largest bank, with KZT 22.0 trillion of assets. About 82% of its income comes from lending, with the rest from foreign-exchange and securities gains (11%), fees (7%) and insurance and other (about 1%). It has three customer businesses: retail banking (B2C, 34% of loans), SME banking (17%) and corporate banking (48.5%), with SME and corporate together forming its B2B arm. The bank also offers insurance, brokerage and leasing services, and has operations in Georgia and Uzbekistan.
What Changed In 1H 2026, And Why It Matters
| What Happened | Why It Matters |
| Profit fell 15%. Net income was KZT 447.6B vs KZT 528.6B a year ago, and Q2 (KZT 212.8B) was the lowest in two years. | Profit funds dividends and supports the share price, so the trend matters more than any single quarter. |
| Funding costs rose faster than income. Interest earned grew 12%, but interest paid grew 22% (deposit rates rose about 10% vs 8.7%), so core lending profit grew only 2.6%. | Like a shop whose costs rise faster than its prices. Four central-bank rate cuts since June (with the policy rate reduced to 15.75% on 23 October) should gradually ease deposit costs. |
| Banks must hold more money in reserve. Margin fell to 6.8% from 7.3% (about 7.2% without the rule change, says the company). | Reserve funds generate little income. This is a regulatory squeeze rather than a pricing problem, but regulations can change again. |
| More set aside for bad loans. Charges rose 69% to KZT 104B, and loans overdue 90+ days are 5.3% of loans (3.0% a year ago; 9.2% in retail). | Households are finding it harder to repay, and money set aside cannot be paid out as dividends. |
| Side businesses went backwards. Insurance swung to a KZT 6.1B loss (from KZT 25.8B profit), and fees fell 19.6% (company cites buy-now-pay-later rules and VAT). | These businesses cushioned 2025 profit. Now the bank leans harder on lending, which is under pressure. |
Management’s 2026 Guidance VS 1H Actuals
| Metric | FY26 Guidance | 1H 2026 Actual | Our Read |
| Net Income | ~KZT 1T | KZT 447.6B | Behind: Needs ~KZT 276B a quarter in 2H, vs KZT 213B in Q2 |
| Return On Equity | ~29% | 24.8% | Behind |
| Loan Growth | 9-12% | 1.2% year to date | Behind |
| Fee Income | -10% (Cut from +5-10%) | -19.6% | Behind |
| Margin / Bad-Loan Charges / Costs vs Income | ~6.8% / ~1.5% / 18-20% | 6.8% / 1.4% / 19.2% | In line |
Dividends: How Sustainable Is The Yield?
Halyk paid KZT 58.19 per share for 2025 (KZT 30.10 in May, KZT 28.09 in September), about 60% of 2025 profit, in line with recent years and above the 50% minimum in its stated policy.
But the yield looks backwards: it reflects a record 2025 profit (KZT 1.06T), the September payment came from earnings kept in earlier years, and the capital ratio fell from 21.0% to 19.0% after the May payout. The next payout depends on 2026 profit, which is falling.
Here is a scenario analysis:
| 2026 Net Income | Dividend Per Share At 50% / 60% Payout | Yield At KZT 370.10 (50% / 60%) |
| KZT 1.0T (Guidance) | KZT 46 / KZT 55 | 12.4% / 14.9% |
| KZT 0.9T (About The 1H Pace) | KZT 41 / KZT 50 | 11.2% / 13.4% |
| KZT 0.8T (Further Slowdown) | KZT 37 / KZT 44 | 9.9% / 11.9% |
Scenario analysis, not a forecast: it assumes about 10.9 billion shares and is before tax.
| Bottom Line: Unless profit recovers to management’s target and the payout stays near 60%, dividend yield is expected to be lower than the ~15.44% recorded as at 10 November 2026; at the 1H pace it would be about 11-13%. Profit funds dividends, and hence it can vary. |
Where It Trades
Halyk Bank is now offered on POEMS, with settlement in USD or SGD. It is listed on KASE (HSBK) and as GDRs in London (HSBK, one GDR = 40 shares). Average daily trading value is KZT 239.85 million (about US$0.53 million), which is small next to larger markets, so buying and selling can be harder than usual.
Key Risks
- Bad Loans: Stage 3 loans (credit-impaired or are in default under the IFRS 9) are 8.6% of loans (vs. 6.6% a year ago), with coverage down to 58% from 73%.
- Economy And Currency: One bank in one economy, exposed to inflation, rates and the tenge (which also moves SGD returns). Regulations can change again.
- Control And Liquidity: ALMEX holds roughly 62% of the shares and Bank of New York (GDR nominee) about 35%, meaning only a small portion of the stock is available for trading, which can reduce liquidity.
Growth Backdrop And What To Watch
A growing economy supports loan demand and deposits. GDP grew 4.2% in January–September 2026, led by construction, manufacturing, transport and trade, and inflation has eased enough for the central bank to cut rates.
| Watch: Q3 results (expected mid-November 2026), loan growth, overdue loans, margin and the tenge. |
Trade Kazakhstan With POEMS
Kazakhstan-listed shares are now available for online trading through POEMS.
| Trading Hours (SGT) | |
| Pre-Opening Session | 2:20PM – 2:30PM |
| Main Continuous Session | 2:30PM – 8:30PM |
For more information, visit POEMS or contact our Global Markets Desk at talktoglobalmarkets@phillip.com.sg.
Sources
- JSC Halyk Bank, Interim Condensed Consolidated Financial Information for the Six Months Ended 30 June 2026 (Unaudited)
- Halyk Group, 1H and 2Q 2026 Results Presentation (August 2026)
- Market data: Bloomberg, 28 Oct 2026; US$ at about KZT 452
- Q3/Q4 2025 profit: Halyk Bank financial statements
- Dividend and shareholding details: Bloomberg
- GDP, loan and deposit data: Kazakh government and National Bank, Oct 2026
Scenario analysis and income splits are our own calculations; the Q3 results date is an estimate.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
About the author
Global Markets Desk (Asia Market)
The Global Markets Desk Asia Market Dealing team specializes in managing Asia Markets, covering key regions like Greater China, Malaysia, Japan, Thailand, and others. In addition to executing client orders, they also provide educational content through market journals and webinars, offering insights into macroeconomics, stock picks, and technical analyses for the Asia market landscape.
 Oracle Corp: BUY Maintained with Target Price of US$225 as Positive Free Cash Flow Comes into Sight
 Nanofilm Technologies: Industrial Segments Drive Growth as Analysts Maintain BUY with S$1.20 Target Price
 Elite UK REIT: Lower Property Expenses Lift Income as BUY Maintained with Target Price of £0.40
 UltraGreen.ai: BUY Maintained With Lower Target Price of US$0.73 — Segmenting to Defend