Stoneweg Europe Stapled Trust Pursues Growth Through Management Internalisation October 15, 2026
Brief Overview
Stoneweg Europe Stapled Trust (SERT) is proposing to internalise its manager for €114 million at a 14% discount to independent valuation, creating a fully integrated European logistics and digital infrastructure platform with approximately €3.2 billion of assets under management. The transaction will be funded through issuing 40 million stapled securities to sponsor SWI Group at €2.00 each, representing a 33% premium to the last traded price of €1.50. Phillip Securities Research maintains a BUY recommendation with an unchanged target price of €1.89, highlighting the deal’s immediate distribution per stapled security (DPS) accretion and growth potential.
Investment Positives
The internalisation presents compelling value creation opportunities for SERT. The acquisition pricing appears attractive at 7.1x P/EBIT based on the effective consideration of €94mn, significantly below the independent valuer’s 10.1x multiple. This favourable valuation provides SERT with immediate financial benefits.
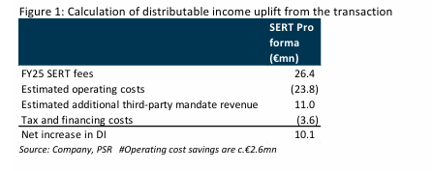
The transaction is expected to deliver substantial DPS accretion of 5.9%, supported by approximately €11 million in third-party asset management fees and the elimination of external management fees. Even when excluding third-party asset management contracts, the deal remains 3.1% DPS accretive, demonstrating the inherent value of the internalisation structure.
Strategically, the transaction brings SERT’s pan-European logistics and light-industrial operating capabilities in-house while preserving access to growth opportunities. Strategic cooperation agreements maintain exclusive access to SWI Group’s European logistics and light-industrial opportunitie, as well as preferred access to specialist data centre capabilities. This supports SERT’s ambition to increase its logistics and light-industrial exposure towards 70% of its portfolio from the current 55.7%.
Upon completion, SERT will manage approximately €3.2 billion of AUM and combine recurring property income with asset management earnings. The internalisation allows SERT to retain acquisition and asset management fees from future acquisitions, creating additional revenue streams and enhancing long-term profitability.
Challenges
The completion of this transaction faces several hurdles, remaining subject to regulatory and third-party consents, as well as securityholder approval at an extraordinary general meeting. These requirements introduce execution risk and potential delays to the anticipated benefits.
Outlook
The internalisation represents a significant strategic shift for SERT, positioning the trust as a fully integrated platform capable of capturing both property income and asset management earnings. The transaction also provides potential for further growth through data centre conversions and SERT’s stake in AiOnX, while maintaining access to SWI Group’s pipeline of opportunities.
Recommendation & Target Price
Phillip Securities Research maintains a BUY recommendation with an unchanged dividend discount model-derived target price of €1.89. The research house remains positive on the transaction given its immediate DPS accretion and potential to capture additional earnings from the integrated operating platform.
Frequently Asked Questions
Q: What is SERT proposing to acquire and at what cost?
A: SERT is proposing to internalise its REIT Manager, BT Trustee-Manager, and pan-European logistics and light-industrial operating platform for a total consideration of €122.4 million, comprising €114 million for the management businesses and €8.4 million for minority co-investment stakes.
Q: How attractive is the acquisition pricing?
A: The acquisition pricing is attractive at 7.1x P/EBIT based on effective consideration of €94 million, which is below the independent valuer's 10.1x multiple and represents a 14% discount to the independent valuation.
Q: What are the expected financial benefits?
A: The transaction is expected to be 5.9% DPS accretive, supported by approximately €11 million in third-party asset management fees and elimination of external management fees. Even excluding third-party contracts, it remains 3.1% DPS accretive.
Q: How will the transaction be funded?
A: The transaction will be funded by issuing 40mn stapled securities to sponsor SWI Group at €2.00 each (€80 million), representing a 33% premium to the last traded price of €1.50.
Q: What assets under management will SERT control after completion?
A: Upon completion, SERT will manage approximately €3.2 billion of AUM and will combine recurring property income with asset management earnings.
Q: What are SERT's strategic objectives for its portfolio composition?
A: SERT aims to increase its logistics and light-industrial exposure towards 70% of its portfolio, up from the current 55.7%.
Q: What conditions must be met for transaction completion?
A: Completion remains subject to regulatory and third-party consents, as well as securityholder approval at an extraordinary general meeting.
Q: What is the current investment recommendation?
A: Phillip Securities Research maintains a BUY recommendation with an unchanged dividend discount model-derived target price of €1.89.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
About the author
Darren Chan
Darren has over seven years of experience across both the buy-side and sell-side. During his tenure as a fund manager, he managed multiple funds and mandates, including dividend income, growth, customised, Singapore-focused, and regionally focused strategies. He holds a First-Class Honours degree in Banking and Finance from the University of London.
 Lion-Phillip S-REIT ETF: Analysts Maintain Positive Outlook Despite Rate Headwinds
 Semiconductor Sector Shows Strong Growth Acceleration Led by Custom ASIC Players
 Software Sector Stages Strong Recovery as AI Concerns Subside
 Frasers Logistics & Commercial Trust Positioned for Growth Through Strong Portfolio and Acquisition Pipeline