Brief Overview
Micron Technology reported strong fourth-quarter 2026 results with revenue and adjusted PATMI within expectations, driven by a dramatic surge in memory pricing. The company secured 10 new strategic customer agreements during the quarter and provided an optimistic outlook for memory market conditions. Phillip Securities Research maintains a BUY recommendation with a raised target price.
Investment Positives
Micron’s strategic positioning has strengthened significantly through new customer agreements. The company signed 26 Strategic Customer Agreements (SCAs) to date, up from 16 in the third quarter of 2026, which management guided to represent over 35% of revenue through 2030. These agreements feature much stricter terms than previous long-term contracts, including cash deposits and take-or-pay contracted volumes with price floors. Two SCAs were extended by a year to 2031, demonstrating customer commitment to long-term supply security.
The financial impact of these agreements is substantial. Remaining performance obligations rose to approximately US$150 billion from US$100 billion in the third quarter, representing 13% higher than FY26 revenue. Financial commitments increased 45% to US$32 billion from US$22 billion, with the majority consisting of cash deposits.
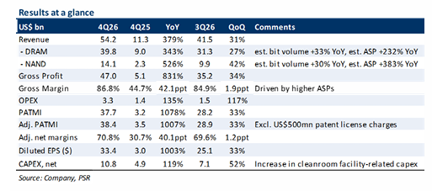
Memory pricing has surged dramatically, driving exceptional profitability. DRAM and NAND average selling prices spiked by an estimated 232% and 383% year-on-year respectively, propelling fourth-quarter 2026 net profit up more than 10-fold to US$38.4 billion. Gross and net margins reached record levels of 87% and 71% respectively, compared to 85% and 70% in the previous quarter.
Supply constraints are expected to persist, supporting pricing strength. Cleanroom space across the industry remains constrained, as new fabrication facility expansions typically require 2-4 years to complete. Management expects memory and storage conditions to be “much tighter” in 2027 and 2028 than the current year, with hyperscalers and high-end processor chip companies prioritising memory supply security through 2031 with approximately 20% cash deposits.
Challenges
The report does not explicitly identify significant investment negatives or challenges facing Micron Technology.
Outlook
Micron anticipates a worsening memory and storage shortage from 2027-2028, which should support continued strong pricing and profitability. The company plans to return all excess cash to shareholders, primarily through buybacks, starting from 9 December 2026 when CHIPS Act restrictions end. The base case projection suggests returning approximately US$70 billion in FY27, equivalent to roughly US$1,100 per share, potentially boosting earnings per share by about 6%.
Recommendation & Target Price
Phillip Securities Research maintains a BUY recommendation with a raised target price of US$1,950, up from the previous US$1,870. The analysts increased FY27 revenue and adjusted PATMI forecasts by 11% and 22% respectively due to expected rises in DRAM and NAND prices, whilst lowering FY27 price-to-earnings assumptions to 12x from 14x.
Frequently Asked Questions
Q: What were Micron's key financial results for Q4 2026?
A: Fourth-quarter 2026 adjusted PATMI surged more than 10-fold year-on-year to US$38.4 billion, with gross and net margins reaching record levels of 87% and 71% respectively, driven by dramatic increases in memory pricing.
Q: How many Strategic Customer Agreements has Micron signed?
A: Micron has signed 26 Strategic Customer Agreements to date, including 10 new agreements in the fourth quarter of 2026, representing over 35% of revenue through 2030.
Q: What makes these new customer agreements different from previous contracts?
A: The SCAs have much stricter terms than past long-term agreements, including cash deposits, take-or-pay contracted volumes, and price floors, providing greater revenue visibility and financial security.
Q: How much have memory prices increased?
A: DRAM and NAND average selling prices increased by an estimated 232% and 383% year-on-year respectively in the fourth quarter of 2026.
Q: What is Micron's outlook for the memory market?
A: Management expects memory and storage shortage conditions to be "much tighter" in 2027 and 2028 compared to current levels, with cleanroom space constraints continuing due to the 2–4-year timeframe required for new fabrication facilities.
Q: How much cash does Micron plan to return to shareholders?
A: The company plans to return all excess cash to shareholders starting 9 December 2026, with a base case projection of approximately US$70 billion in FY27, equivalent to roughly US$1,100 per share.
Q: What is the current investment recommendation?
A: Phillip Securities Research maintains a BUY recommendation with a target price of US$1,950, raised from the previous target of US$1,870.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.