CapitaLand China Trust: Refinancing Capacity Intact Despite Weaker Rental Fundamentals

Phillip Bond Desk

 |   02 Nov 2026  |    28 views

Company Overview

CapitaLand China Trust (CLCT) is a Singapore-listed REIT with 17 properties across mainland China, comprising eight retail malls, five business parks and four logistics parks. Retail malls contribute 70.6% of gross rental income (GRI), followed by business parks at 26.0% and logistics parks at 3.4%. CLCT is sponsored by CapitaLand Investment, which holds an approximately 25% stake.


Credit View

CLCT’s near-term debt-servicing capacity remains adequate, supported by lower financing costs, a sizeable unencumbered asset base and demonstrated refinancing access. However, persistent negative rental reversions, particularly in business parks, continue to weigh on underlying property income. With 62.7% of debt maturing over 2027–2029 and limited internally retained cash for deleveraging, refinancing execution remains important. Further rental weakness and property valuation declines could narrow leverage headroom and constrain medium-term credit flexibility.


Credit Performance Highlights

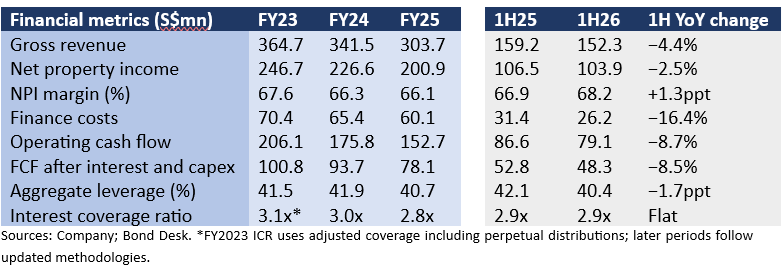
Three-year financial performance and latest interim results
Factsheets

Property earnings have weakened since FY2023, with underlying rental pressure becoming more evident in 3Q26. NPI declined 18.6% from S$246.7mn in FY2023 to S$200.9mn in FY2025, reflecting asset divestments, weaker rental performance and RMB depreciation. In 1H26, NPI fell 2.5% YoY to S$103.9mn, mainly due to the absence of CapitaMall Yuhuating’s contribution, while same-store NPI grew 1.3%. However, operating performance weakened in 3Q26. For 9M26, NPI declined 3.9% YoY to RMB820.6mn, with same-store NPI falling 0.8% despite a 3% reduction in property operating expenses. In SGD terms, NPI increased 1.9% YoY due to favourable RMB translation, partly offsetting the weaker underlying rental performance.


Portfolio Operating Performance

Retail occupancy remains resilient, with rental pricing continuing to soften. Occupancy stood at 97.2% in September 2026, supported by 3.5% YoY growth in tenant sales and 1.9% growth in shopper traffic. Excluding automobile sales, tenant sales increased 8.4%, outperforming China’s 1.1% retail sales growth in 9M26. Nevertheless, rental reversion remained negative at −3%, reflecting continued competitive leasing conditions. CBRE reported a 1.3% YTD decline in nationwide shopping mall ground-floor rents in 3Q26. With 41.5% of retail GRI expiring in 2027, continued negative rental reversions could constrain income growth despite high occupancy. Retail remains CLCT’s main earnings stabiliser, although rental pricing power has yet to show a sustained recovery.

Business parks remain the principal operating risk, with significant lease expiries exposing earnings to further rental resets. Occupancy declined from 91% in FY2023 to 85.7% in September 2026, while rental reversion deteriorated from +1.6% to −12.6%. Weakness is particularly evident at the Hangzhou business parks, where occupancy stood at 73.4% and 72.5%, and Ascendas Innovation Towers in Xi’an, where occupancy fell to 76.3%. Around 67.4% of business park GRI is due to expire over 2027–2028. Continued negative rental reversions and potential tenant vacancies could weaken recurring property income and increase pressure on future valuations.

Logistics operating performance has stabilised, but the segment provides limited earnings offset. Occupancy improved to 98.6% in September 2026 from 96.6% in June 2025, while rental reversion narrowed to −1.3% from −24.5% in FY2025. However, nationwide logistics rents declined 4.1% QoQ in 3Q26, suggesting that leasing conditions remain competitive. Given its 3.4% contribution to total GRI, logistics improvements are unlikely to materially offset prolonged business park weakness.


Cash Flow and Liquidity

Operating cash generation remains sufficient for interest servicing and capital expenditure, although limited cash retention constrains organic deleveraging. In 1H26, operating cash flow declined 8.7% YoY to S$79.1mn, reflecting lower property income following the CapitaMall Yuhuating divestment and higher cash tax payments. Cash interest paid fell 9.2% to S$24.8mn, while FCF after interest and capex remained positive at S$48.3mn. However, cash distributions to unitholders, perpetual securities holders and non-controlling interests totalled S$52.4mn, exceeding FCF by S$4.1mn. While the shortfall was modest and affected by distribution timing, it highlights limited internally retained cash for debt reduction. CLCT also provided a one-off distribution top-up in FY2025 using historical divestment gains, funded through debt. Consolidated cash stood at S$223.2mn as at June 2026, with only S$1.5mn was held directly at the trust level.


Leverage and Debt-Servicing Capacity

Leverage remains elevated despite historical debt reduction. Gross borrowings declined 13% from S$1.96bn in FY2023 to S$1.70bn in FY2025. However, aggregate leverage remained around 41%, as property divestments and valuation declines also reduced the asset base. In 3Q26, total debt increased by approximately S$44mn QoQ to S$1.78bn, lifting aggregate leverage to 41.1% from 40.4% in June. This leaves 8.9 percentage points of headroom below the 50% regulatory limit.

Property valuation pressure could further constrain leverage headroom. CLCT recognised investment property fair-value losses of S$89.7mn in FY2024 and S$50.5mn in FY2025. Investment property carrying values rose from S$4.2bn at end-2025 to S$4.32bn in June 2026, mainly due to S$114.9mn of favourable currency translation, with no additional fair-value gain recognised. The FY2025 financial statements also disclosed a material valuation uncertainty clause from one independent valuer, reflecting heightened uncertainty in China’s property market. Continued rental weakness could therefore place pressure on future valuation assumptions and increase leverage even without additional borrowings.

Lower financing costs have supported interest coverage. Average borrowing costs declined from 3.36% in September 2025 to 3.04% in September 2026, helping ICR recover to 3x from 2.8x at FY2025.
Factsheets

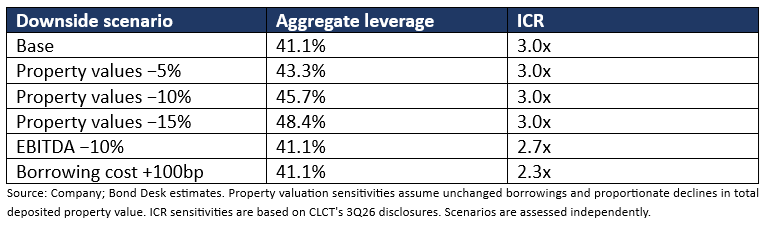
Under our sensitivity analysis, a 15% decline in deposited property values would raise aggregate leverage to approximately 48.4%, leaving only 1.6 percentage points below the regulatory limit. Meanwhile, management estimates that a 10% decline in EBITDA would reduce ICR to 2.7x, while a 100bp increase in borrowing costs would lower coverage to 2.3x. Although these scenarios remain within regulatory thresholds individually, they demonstrate CLCT’s vulnerability to simultaneous earnings, valuation and financing pressures.


Refinancing Capacity and Bondholder Protection

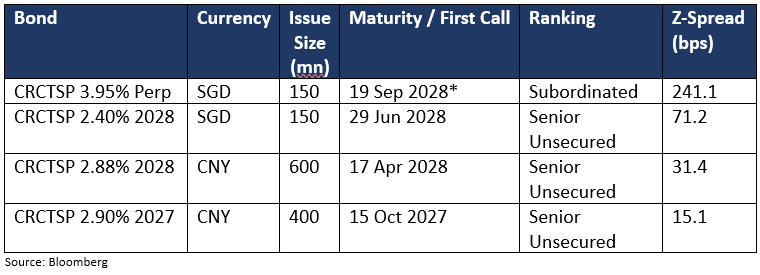
Refinancing risk remains manageable despite sizeable upcoming maturities. As at September 2026, S$1.12bn of debt (62.7% of total borrowings) was due in 2027–2029. Average debt maturity shortened to 2.7 years from 3.4 years a year earlier. CLCT refinanced its RMB600mn October 2026 bond through bank facilities at approximately 2.3% versus the previous 3.8% coupon. This reflects lower RMB borrowing rates and continued access to bank funding. While the refinancing provides some relief to interest costs, the sizeable maturity pipeline leaves CLCT exposed to future funding conditions.

A substantial unencumbered asset base supports refinancing flexibility. As at June 2026, CLCT had approximately S$3.34bn of unencumbered investment properties, representing 77.2% of its S$4.32bn portfolio. This compares with S$1.59bn of unsecured borrowings, providing 2.1x indicative gross book-value coverage.


Bond Outstanding
Factsheets

Related Articles

IOI Properties Group: Growing Recurring Earnings Support Debt Servicing

IOI Properties Group Berhad (IOIPG) is a Malaysia-listed property group with operations in Malaysia, Singapore and China.

 |   06 Nov 2026

Baiduri Bank Sendirian Berhad Launched S$280mn 2.95% 3-Year SGD Bond: Credit View

Baiduri Bank was established in 1994 and commenced retail banking operations in 1996. It is Brunei Darussalam's second-largest bank and one of two domestic systemically important banks (D-SIBs) designated by the Brunei Darussalam Central Bank (BDCB).

 |   28 Oct 2026

BNP Paribas 8.00% Perpetual AT1; 2.588% Tier 2 Due 2035: Credit View

BNP Paribas is a global systemically important bank (G-SIB) with diversified operations spanning retail banking, corporate and institutional banking, wealth management, asset management and insurance.

 |   21 Oct 2026

Disclaimers


These commentaries are intended for general circulation. It does not have regard to the specific investment objectives, financial situation and particular needs of any person who may receive this document. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of the units and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. Investors may wish to seek advice from a financial adviser before investing. In the event that investors choose not to seek advice from a financial adviser, they should consider whether the investment is suitable for them.

The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the "Research") contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.

Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.

IMPORTANT INFORMATION

This material is provided by Phillip Capital Management (S) Ltd (“PCM”) for general information only and does not constitute a recommendation, an offer to sell, or a solicitation of any offer to invest in any of the exchange-traded fund (“ETF”) or the unit trust (“Products”) mentioned herein. It does not have any regard to your specific investment objectives, financial situation and any of your particular needs. You should read the Prospectus and the accompanying Product Highlights Sheet (“PHS”) for key features, key risks and other important information of the Products and obtain advice from a financial adviser (“FA“) pursuant to a separate engagement before making a commitment to invest in the Products. In the event that you choose not to obtain advice from a FA, you should assess whether the Products are suitable for you before proceeding to invest. A copy of the Prospectus and PHS are available from PCM, any of its Participating Dealers (“PDs“) for the ETF, or any of its authorised distributors for the unit trust managed by PCM.  

An ETF is not like a typical unit trust as the units of the ETF (the “Units“) are to be listed and traded like any share on the Singapore Exchange Securities Trading Limited (“SGX-ST”). Listing on the SGX-ST does not guarantee a liquid market for the Units which may be traded at prices above or below its NAV or may be suspended or delisted. Investors may buy or sell the Units on SGX-ST when it is listed. Investors cannot create or redeem Units directly with PCM and have no rights to request PCM to redeem or purchase their Units. Creation and redemption of Units are through PDs if investors are clients of the PDs, who have no obligation to agree to create or redeem Units on behalf of any investor and may impose terms and conditions in connection with such creation or redemption orders. Please refer to the Prospectus of the ETF for more details.  

Investments are subject to investment risks including the possible loss of the principal amount invested. The purchase of a unit in a fund is not the same as placing your money on deposit with a bank or deposit-taking company. There is no guarantee as to the amount of capital invested or return received. The value of the units and the income accruing to the units may fall or rise. Past performance is not necessarily indicative of the future or likely performance of the Products. There can be no assurance that investment objectives will be achieved.  

Where applicable, fund(s) may invest in financial derivatives and/or participate in securities lending and repurchase transactions for the purpose of hedging and/or efficient portfolio management, subject to the relevant regulatory requirements. PCM reserves the discretion to determine if currency exposure should be hedged actively, passively or not at all, in the best interest of the Products.  

The regular dividend distributions, out of either income and/or capital, are not guaranteed and subject to PCM’s discretion. Past payout yields and payments do not represent future payout yields and payments. Such dividend distributions will reduce the available capital for reinvestment and may result in an immediate decrease in the net asset value (“NAV”) of the Products. Please refer to <www.phillipfunds.com> for more information in relation to the dividend distributions.  

The information provided herein may be obtained or compiled from public and/or third party sources that PCM has no reason to believe are unreliable. Any opinion or view herein is an expression of belief of the individual author or the indicated source (as applicable) only. PCM makes no representation or warranty that such information is accurate, complete, verified or should be relied upon as such. The information does not constitute, and should not be used as a substitute for tax, legal or investment advice.  

The information herein are not for any person in any jurisdiction or country where such distribution or availability for use would contravene any applicable law or regulation or would subject PCM to any registration or licensing requirement in such jurisdiction or country. The Products is not offered to U.S. Persons. PhillipCapital Group of Companies, including PCM, their affiliates and/or their officers, directors and/or employees may own or have positions in the Products. Any member of the PhillipCapital Group of Companies may have acted upon or used the information, analyses and opinions herein before they have been published. 

This advertisement has not been reviewed by the Monetary Authority of Singapore.  


Phillip Capital Management (S) Ltd (Co. Reg. No. 199905233W)  
250 North Bridge Road #06-00, Raffles City Tower ,Singapore 179101 
Tel: (65) 6230 8133 Fax: (65) 65383066 www.phillipfunds.com

?>