Adobe Inc – No inflection point in sight October 6, 2026
Brief Overview
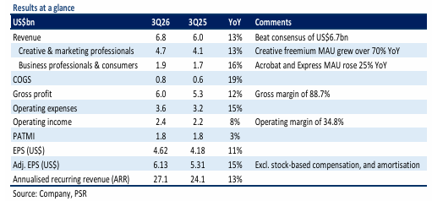
Adobe delivered third quarter fiscal 2026 results that met expectations, with revenue and adjusted profit after tax and minority interests achieving 74% and 78% of full-year forecasts respectively. Growth was primarily driven by the Adobe Creative Cloud Pro deal, whilst Creative freemium monthly active users grew over 70% year-on-year, surpassing 100 million. Management raised fiscal 2026 guidance only marginally, and leadership continuity was assured with Chakravarthy set to succeed Shantanu Narayen as CEO in December 2026.
Investment Positives
Adobe demonstrates strengthening activity across its Creative products portfolio. Creative & Marketing Professionals revenue grew 13% year-on-year to US$4.65 billion, supported by continued momentum in Creative Cloud Teams and Enterprise offerings. The freemium strategy is gaining significant traction, with Creative freemium monthly active users surpassing 100 million and growing over 70% year-on-year, driven by strong adoption of Firefly, Express, Premiere, Photoshop and Lightroom.
Artificial intelligence engagement continues to deepen across Adobe’s platform, with credit consumption accelerating quarter-on-quarter. Firefly annual recurring revenue across the Firefly App and credit packs grew 40% quarter-on-quarter, reflecting rising monetisation of Adobe’s AI offerings and the company’s AI-first annual recurring revenue exceeding US$650 million.
The document workflow segment shows ongoing expansion, with Business Professionals & Consumers revenue increasing 16% year-on-year to US$1.91 billion. This growth was supported by the strong adoption of Acrobat and Express products. Combined monthly active users exceeded 900 million, growing over 25% year-on-year, whilst Acrobat AI Assistant monthly active users doubled quarter-on-quarter. Adobe continues expanding Acrobat into an AI-powered productivity platform, incorporating new capabilities such as document summarisation, interactive reports, presentation slides and knowledge extraction across large document collections, driving both engagement and enterprise adoption.
Challenges
Despite the strong AI performance, Adobe’s fiscal 2026 ending annual recurring revenue growth guidance was maintained at 10.2% compared to 11.5% in fiscal 2025, reflecting a continued emphasis on user acquisition and engagement over monetisation. This suggests the company has not yet reached an inflection point where its AI investments translate into accelerated revenue growth.
Outlook
The stock’s recovery has been supported by evidence that AI complements Adobe’s business model, strong AI engagement metrics, and rising confidence in freemium monetisation strategies. However, the maintained annual recurring revenue growth guidance indicates that Adobe continues to prioritise user base expansion over immediate revenue acceleration.
Recommendation & Target Price
Phillip Securities Research maintains a neutral recommendation on Adobe Inc. The target price has been raised to US$261 from the previous US$203, implying a 14.3 times fiscal 2026 price-to-earnings ratio, which remains below the stock’s two-year average of 16 times.
Frequently Asked Questions
Q: How did Adobe's third quarter fiscal 2026 results perform against expectations?
A: Revenue and adjusted profit after tax and minority interests met expectations at 74% and 78% of full-year fiscal 2026 forecasts respectively.
Q: What drove Adobe's growth in the quarter?
A: Growth was driven mainly by the Adobe Creative Cloud Pro deal, with Creative freemium monthly active users growing over 70% year-on-year, surpassing 100 million.
Q: How is Adobe's AI strategy performing financially?
A: AI-first annual recurring revenue exceeded US$650 million, whilst Firefly annual recurring revenue across the Firefly App and credit packs grew 40% quarter-on-quarter, with credit consumption accelerating quarter-on-quarter.
Q: What are the key growth metrics for Adobe's document business?
A: Business Professionals & Consumers revenue increased 16% year-on-year to US$1.91 billion, with combined monthly active users exceeding 900 million, growing over 25% year-on-year, and Acrobat AI Assistant monthly active users doubling quarter-on-quarter.
Q: How did management adjust their guidance?
A: Management raised fiscal 2026 guidance only marginally, with revenue and adjusted earnings per share guidance increasing by 0.2% and 0.3% respectively, whilst maintaining ending annual recurring revenue growth guidance at 10.2%.
Q: What leadership changes are planned at Adobe?
A: Chakravarthy will succeed Shantanu Narayen as CEO on 1 December 2026, ensuring leadership continuity.
Q: What is the investment recommendation and target price?
A: Phillip Securities Research maintains a neutral recommendation and raised the target price to US$261 from US$203, implying a 14.3 times fiscal 2026 price-to-earnings ratio.
Q: Why does the analyst believe there is no inflection point in sight?
A: Despite AI-first annual recurring revenue exceeding US$650 million, fiscal 2026 ending annual recurring revenue growth guidance was maintained at 10.2% versus 11.5% in fiscal 2025, reflecting continued emphasis on user acquisition and engagement over monetisation.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
 Oracle Corp – Revenue Inflection as AI Monetisation Gains Traction
 Sasseur REIT Shows Strong Growth Momentum Ahead of Anniversary Sales
 Singapore REITs Show Resilience Despite Rate Pressures, Analysts Maintain Overweight Stance
 iX Biopharma Ltd – Gaining altitude with significant approvals