Maximizing Retirement Wealth: How to Invest CPF-OA and SRS in SGX ETFs October 20, 2026
For working professionals in Singapore, building a comfortable retirement nest egg requires more than just relying on monthly salary savings. The Singapore government offers two powerful retirement savings vehicles: the Central Provident Fund Ordinary Account (CPF-OA) and the Supplementary Retirement Scheme (SRS).
While keeping cash in these accounts guarantees safety, holding idle funds during inflationary periods risks eroding your long-term purchasing power. By strategically investing CPF-OA and SRS funds into Exchange-Traded Funds (ETFs) listed on the Singapore Exchange (SGX), you can harness market growth while enjoying tax efficiency.
1. The Baseline: Understanding Your Minimum Target Returns
Before investing, consider both the returns you may gain by keeping your money in its existing account and the potential benefits and risks of investing it instead. As a rule of thumb, your expected investment returns should be higher than the risk-free interest rate guaranteed by each account since investing involves taking on greater risks:
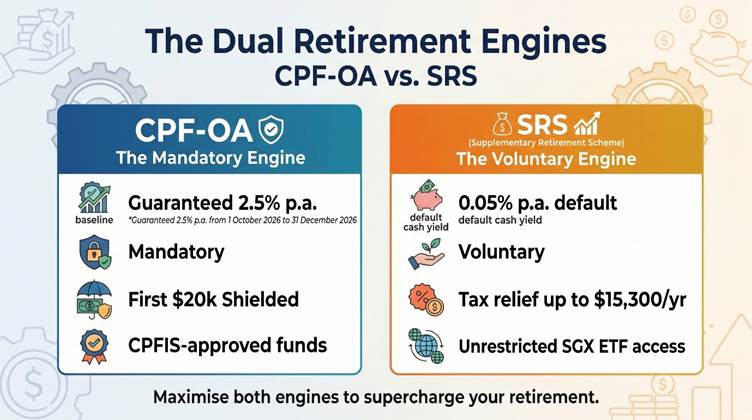
· CPF-OA Target Return (2.50% p.a. base):
CPF-OA provides a risk-free guaranteed return of 2.5% per year (and up to 3.5% on the first S$20,000 of OA balance via extra CPF interest). Additional CPF interest may also apply to eligible balances, depending on your age and total CPF savings. However, additional interest earned on OA savings is credited to your Special Account or Retirement Account, rather than retained in the OA. Investing your CPF-OA only makes sense if your target portfolio can consistently yield 5.0%–7.0% per year over a long horizon (10+ years).
· SRS Target Return (0.05% p.a. base):
The SRS is a voluntary retirement savings scheme that offers tax benefits to eligible contributors. Uninvested cash in an SRS account earns a basic bank savings rate of just 0.05% per year. Leaving SRS funds idle will result in a loss of buying power to inflation over time.
The Power of Compounding S$10,000 Over 20 Years
| Investment Strategy | Projected Return (p.a.) | Value After 20 Years |
| Idle in SRS | 0.05% | ~S$10,100 |
| Idle in CPF-OA (Base Rate) | 2.50% | ~S$16,386 |
| Core SGX ETF Strategy | 6.50% (Projected) | ~S$35,236 |
Investing SRS funds gives you the opportunity to seek higher returns over time, although this comes with investment risk. The choice of investments should reflect your financial objectives, risk tolerance and retirement timeline.
2. Option 1: Investing CPF-OA via CPFIS
Rules & Eligibility
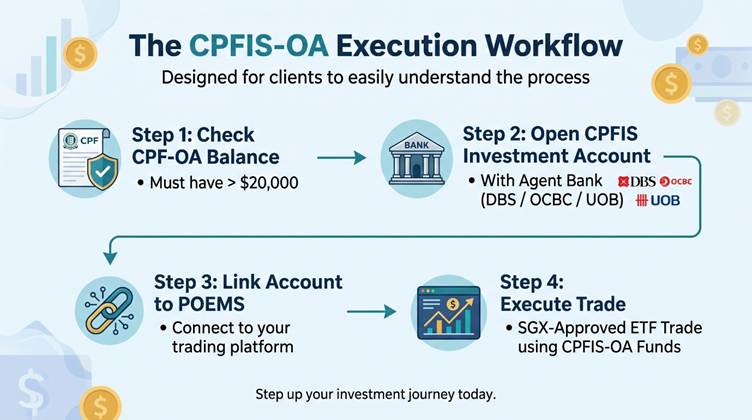
To invest CPF-OA funds under the CPF Investment Scheme (CPFIS-OA), you must:
- Be at least 20 years old and not an undischarged bankrupt.
- Maintain a mandatory minimum balance of S$20,000 in your CPF-OA (only funds above S$20,000 can be invested).
- Complete the online CPFIS Self-Assessment Test (SAT).
- Opened a CPF Investment Account with one of the three approved agent banks
Note: Not all investments are eligible under CPFIS. Investors should check the scheme’s requirements and the eligibility of specific products before committing their savings.
Popular CPFIS-Approved SGX ETFs
CPFIS sets strict limits on management fees and risk levels. Top approved ETFs on SGX include:
| Ticker | ETF Name | Asset Class / Focus | CPFIS Risk Level |
| ES3.SI | SPDR Straits Times Index ETF | Top 30 Singapore Listed Companies | Low to Medium Risk |
| G3B.SI | Nikko AM Singapore STI ETF | Top 30 Singapore Listed Companies | Low to Medium Risk |
| A35.SI | ABF Singapore Bond Index Fund | Singapore Government & AAA-Rated Bonds | Low Risk |
3. Option 2: Supercharging Retirement with the Supplementary Retirement Scheme (SRS)
Tax Relief Mechanics
SRS is a voluntary account that helps you save on taxes today while building wealth for tomorrow.
- Annual Contribution Caps: Up to S$15,300 for Singaporeans/PRs (and S$35,700 for foreigners).
- Tax Benefit: Every dollar contributed directly reduces your taxable income for that year (e.g., contributing $15,300 to SRS reduces your taxable assessable income for the year by $15,300).
- Tax-Free Withdrawals at Retirement: 50% of SRS withdrawals are tax-exempt if made on or after the statutory retirement age (age 63, moving to 64 in July 2026 and 65 by 2030).
Broader Choice of Investments
Unlike CPF-OA, SRS funds can be invested in a wider range of eligible products, such as any ETF listed on SGX, allowing for broader global and sector exposure. e available choices differ from those under CPFIS, so investors should verify whether a particular product is eligible before investing. Examples of ETFS to research include:
- Regional Technology: Lion-OCBC Securities Hang Seng TECH ETF (HST.SI)
- Real Estate Income (S-REITs): Lion-Phillip S-REIT ETF (CLR.SI) or NikkoAM-STC Asia REIT ETF (CFA.SI)
- Global / US Equities: SPDR S&P 500 ETF (S27.SI)
4. Sample Model Portfolios for CPF-OA & SRS
The appropriate allocation depends on your retirement horizon, financial circumstances, risk tolerance and existing investments. The following examples illustrate how investors might approach portfolio construction
Strategy A: Conservative Growth & Income (CPF-OA Focus)
Designed for stability with steady dividend income:
- 70% Allocation: SPDR STI ETF (ES3.SI) — Captures ~3.5%–4.5% annual dividend yield from Singapore’s top banks and companies.
- 30% Allocation: ABF Singapore Bond Index Fund (A35.SI) — Provides fixed income backed by Singapore Government Securities.
Strategy B: Global Growth & Yield (SRS Focus)
Designed for long-term wealth growth and income:
- 50% Allocation: SPDR S&P 500 ETF (S27.SI) — Broad exposure to the top 500 US companies.
- 30% Allocation: Lion-OCBC Hang Seng TECH ETF (HST.SI) — Targeted growth exposure to major Asian tech leaders.
- 20% Allocation: Lion-Phillip S-REIT ETF (CLR.SI) — Generates regular dividend payouts from Singapore Real Estate Investment Trusts.
5. Key Considerations & Best Practices
- Mind the Transaction Fees: Transaction fees, agent bank charges and other applicable costs can affect your net returns, particularly when making smaller investments. For example, CPFIS trades incur agent bank clearing fees ($2 to $2.50 per transaction for CPFIS). Review the full fee schedule and consider how frequently you trade. Investing larger amounts less frequently may reduce the proportion of costs relative to the amount invested, although this should not come at the expense of an appropriate investment strategy.
- Reinvest Dividend Distributions: Dividends and fund distributions can contribute to long-term portfolio growth. If your objective is to accumulate retirement savings, reinvesting these proceeds may help your investments compound over time. Cash dividends from CPFIS and SRS investments flow back into your agent bank account. Set a calendar reminder to manually reinvest these funds periodically so your wealth keeps compounding.
- Avoid Early SRS Withdrawals: Withdrawing SRS cash before reaching your statutory retirement age incurs a 5% penalty, and 100% of the withdrawn amount will be taxed as income. Plan your contributions with your expected cash-flow needs in mind, and avoid committing money that you may need access to before retirement.
5. Key Takeaways
CPF-OA and SRS serve different purposes, and investing through either scheme involves trade-offs.
- Beat the Hurdle Rates: CPF-OA provides a base interest rate (2.5% p.a.) and additional interest may apply under CPF rules, while SRS offers potential tax benefits and access to eligible investments. The decision is not simply about seeking the highest possible return. It is about understanding the benefits you may be giving up, the risks you are taking, and how each investment fits into your broader retirement plan.
- Optimise Taxes & Costs: Utilise SRS for immediate dollar-for-dollar tax deductions and batch your CPFIS trades to keep agent bank fees low.
- Stay Invested: Automate dividend reinvestments and hold your SRS positions until reaching the statutory retirement age to avoid early withdrawal penalties.
As always, before investing, review your financial needs, compare the costs and investment options available, and ensure that your portfolio is appropriate for your circumstances. A well-considered strategy should support your retirement goals without exposing you to risks you cannot afford to take.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
About the author
Mr Teo Huan Zi
Mr Teo Huan Zi graduated from Nanyang Technological University (NTU) in 2014 with a Bachelor’s degree in Business, majoring in Banking and Finance. He currently serves as a dealing manager with a team of more than 10 equity specialists. Additionally, he frequently conducts seminars and webinars to empower his clients with financial and investment knowledge, including fundamental analysis and technical analysis.
 ETF Monthly Review: Mixed September Performance with Muted October Outlook Expected
 PhillipCapital Morning Webinar: Market Updates and Analysis for 21 Sep 2026
 Investing in the AI Revolution: A Guide to Semiconductor & Ecosystem ETFs
 Phillip SING Income ETF Reaches All-Time High Dividend with Banking Sector Focus