Q & M Dental Group Awaits Inorganic Growth Amid Challenging Operating Environment September 25, 2026
Brief Overview
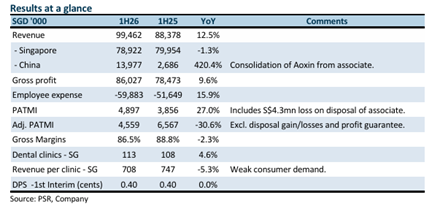
Q & M Dental Group’s 1H26 results fell short of expectations, with revenue and adjusted profit after tax representing just 45% and 25% of full-year forecasts respectively. The company faced softer-than-expected performance in Singapore and China, whilst higher finance costs from pending acquisitions have weighed on earnings. Despite these challenges, the analyst maintains a BUY recommendation with expectations of seasonal recovery and inorganic growth opportunities.
Investment Positives
The primary investment case centres on significant pending acquisitions that are expected to drive future growth. Q & M Dental has S$146 million in pending acquisitions of dental clinics across Australia (S$107 million) and Thailand (S$39 million). The acquisition structure involves S$92 million in cash payments and 86.7 million shares valued at S$0.70 each.
According to the analyst, these acquisitions will boost earnings per share by at least one cent following the new share issuance. The analyst has incorporated profit-guaranteed earnings from both Australia and Thailand acquisitions into their forward valuations, albeit at a 50% discount to reflect execution risk.
Looking ahead, the analyst expects a seasonal recovery in Singapore during the second half of FY26, coupled with improving revenue intensity as the company pursues initiatives to elevate the complexity of dental care services. In China, Q & M Dental plans to launch a new hospital in 2H26, which should support the division’s performance.
Challenges
The company faces significant operational headwinds across its key markets. Whilst reported revenue grew 12.5% to S$99.5 million, this growth was primarily driven by the consolidation of Aoxin Q&M Dental from associate status into China’s revenue figures. Underlying performance was weaker, with Singapore revenue declining 1.3% and revenue per clinic in Singapore falling 5.3% due to weak consumer demand.
The China operations face particular challenges from government-imposed price controls and subdued demand stemming from the broader economic environment. Aoxin specifically recorded a 21% revenue decline in 1H26, highlighting the pressures facing the Chinese dental market.
Discretionary demand for dental services in Singapore proved particularly weak during the first quarter, though some recovery was evident in the second quarter.
Outlook
The analyst has lowered FY26 adjusted earnings expectations by 30% to S$12.7 million, reflecting the challenging operating environment. However, expectations remain for improvement driven by seasonal factors in Singapore and the launch of new facilities in China during the second half of the financial year.
Recommendation & Target Price
Phillip Securities Research maintains a BUY recommendation with an unchanged target price of S$0.71. The analyst has rolled forward valuations to FY27 to incorporate the expected profit-guaranteed earnings from the Australian and Thailand acquisitions.
Frequently Asked Questions
Q: What were the key disappointments in Q & M Dental's 1H26 results?
A: Revenue and adjusted profit after tax were only 45% and 25% of the full-year forecast respectively, with softer performance in Singapore and China, plus higher finance costs from pending acquisitions.
Q: How significant are the pending acquisitions?
A: Q & M Dental has S$146 million in pending acquisitions in Australia (S$107 million) and Thailand (S$39 million), funded through S$92 million cash and 86.7 million shares at S$0.70 each.
Q: What impact will the acquisitions have on earnings?
A: The acquisitions are expected to boost earnings per share by at least one cent following the new share issuance.
Q: Why did Singapore revenue decline despite overall revenue growth?
A: Singapore revenue fell 1.3% due to weak discretionary demand for dental services, whilst overall growth came from consolidating Aoxin Q&M Dental into China's revenue.
Q: What challenges is the China business facing?
A: The China operations are under pressure from government price controls and weak demand due to the economic environment, with Aoxin recording a 21% revenue decline in 1H26.
Q: What improvements does the analyst expect in the second half?
A: The analyst expects seasonal recovery in Singapore with improving revenue intensity, plus the launch of a new hospital in China during 2H26.
Q: How much did the analyst lower earnings forecasts?
A: The analyst reduced FY26 adjusted earnings expectations by 30% to S$12.7 million.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
About the author
Paul Chew
Paul has more than 25 years of experience as a fund manager and sell-side analyst. He currently covers sectors such as healthcare, electronics, telecommunications, conglomerates, small caps, and strategy.
He graduated from Monash University and has completed both his Chartered Financial Analyst and Australian CPA programme.
 iX Biopharma Ltd – Gaining altitude with significant approvals
 Palo Alto Networks Inc – Highest Sales Growth in 9 Years
 Phillip Singapore Monthly: August 2026 – Trading at a Justified Premium
 Singapore Aviation Sector Faces Fuel Price Surge and Margin Pressure