Wells Fargo Maintains Growth Momentum Despite Rate Headwinds October 21, 2026
Overview
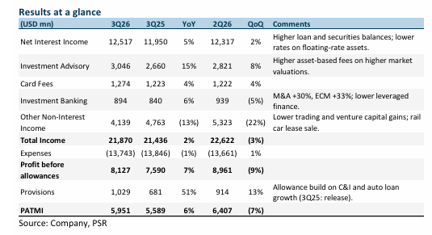
Wells Fargo reported third-quarter 2026 earnings of US$6 billion, up 6% year-on-year, though below analyst estimates due to lower net interest income and trading gains. Investment advisory fees rose 15% as client assets grew, while investment banking fees increased 6% from market share gains. The company maintained its BUY rating with a reduced target price of US$105, down from US$115.
Investment Positives
Wells Fargo demonstrated strong operational efficiency through successful cost management initiatives. Expenses fell 1% year-on-year despite a 15% increase in revenue-related expenses, as non-revenue-related expenses declined 4%. The bank achieved this through workforce optimisation, with headcount falling 8% year-on-year to 194,000, marking the 24th consecutive quarterly decline. This drove efficiency ratio improvement to 63% from 65% in the prior year, with management expecting to absorb approximately US$400 million of higher revenue-related expenses within unchanged full-year guidance. The bank’s commercial client franchise powered impressive balance sheet growth. Average loans surged 11% year-on-year to US$1.03 trillion, led by Corporate and Investment Banking (+19%), Wealth and Investment Management securities-based lending (+16%), and Commercial Banking (+10%). Deposits mirrored this growth, rising 11% year-on-year to US$1.48 trillion, with Corporate and Investment Banking up 22% and Commercial Banking advancing 16%. Auto balances showed particularly strong momentum, climbing 31% year-on-year. Credit quality metrics remained robust throughout this expansion. The net charge-off ratio improved to 0.38% from 0.40% in the prior year quarter, whilst nonperforming assets declined to 0.70% of loans from 0.83%. Investment advisory fees benefited from market tailwinds, rising 15% year-on-year as higher stock and bond prices lifted Wealth and Investment Management client assets by 11%. Investment banking fees grew 6% year-on-year as strategic hiring enhanced market share in mergers and acquisitions and equity capital markets.
Challenges
Lower interest rates compressed loan yields, offsetting the benefit of strong loan growth on net interest income performance. A sharp move in interest rates in late September also slowed client activity in fixed income, currencies and commodities, impacting trading revenues. The bank faced headwinds from lost lease income following its rail car business sale and lower mortgage banking fees, which left non-interest income down 1% year-on-year despite gains in other areas.
Outlook
Wells Fargo maintained its full-year 2026 net interest income guidance at approximately US$50 billion, though it lowered Markets net interest income expectations to approximately US$1.8 billion from the previous US$2 billion estimate. The bank expects continued earnings growth from balance sheet expansion capabilities, with maturing card vintages and investment banking share gains contributing to earnings into fiscal year 2027. The company targets return on tangible common equity of 17% to 18%, supported by ongoing cost discipline and revenue growth initiatives.
Recommendation & Target Price
Phillip Securities Research maintains a BUY recommendation on Wells Fargo with a target price of US$105, reduced from the previous US$115. The firm lowered fiscal year 2026 earnings estimates by 8% due to reduced net interest income, investment advisory, and other non-interest income projections. The valuation assumes 1.85x fiscal year 2026 price-to-book value and return on equity estimate of 16.7%.
Frequently Asked Questions
Q: What drove Wells Fargo's third-quarter 2026 earnings performance?
A: Earnings rose 6% year-on-year to US$6 billion, driven by strong loan growth and effective cost management, though results were below estimates due to lower net interest income and trading gains.
Q: How did the bank achieve cost savings despite revenue growth?
A: Non-revenue-related expenses fell 4% as headcount declined 8% year-on-year to 194,000, the 24th consecutive quarterly reduction, allowing total expenses to fall 1% despite 15% higher revenue-related expenses.
Q: What areas showed the strongest loan growth?
A: Corporate and Investment Banking led with 19% growth, followed by Wealth and Investment Management securities-based lending at 16% and Commercial Banking at 10%, contributing to overall 11% loan growth.
Q: How did credit quality perform during this growth period?
A: Credit metrics improved with the net charge-off ratio falling to 0.38% from 0.40% and nonperforming assets declining to 0.70% of loans from 0.83% year-on-year.
Q: What challenges did Wells Fargo face in the quarter?
A: Lower interest rates compressed loan yields, late-September rate movements slowed trading client activity, and the bank experienced lost lease income from rail car sales plus lower mortgage banking fees.
Q: What is the investment thesis for maintaining a BUY rating?
A: The bank can now expand its balance sheet with both loans and deposits up 11% year-on-year, whilst cost cuts keep expenses flat as revenue grows, with maturing card vintages and investment banking gains supporting future earnings.
Q: Why was the target price reduced?
A: The target price fell to US$105 from US$115 due to 8% lower fiscal year 2026 earnings estimates from reduced net interest income, investment advisory, and other non-interest income projections.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
About the author
Glenn Thum
Phillip Securities Pte Ltd
Glenn covers the Banking and Finance sector. He has had 3 years of experience as a Credit Analyst in a Bank, where he prepared credit proposals by conducting consistent critical analysis on the business, market, country and financial information. Glenn graduated with a Bachelor of Business Management from the University of Queensland with a double major in International Business and Human Resources.
 Raffles Education Set for Growth Pivot as Focus Shifts to ASEAN K-12 Expansion
 Nanofilm Technologies Targets Growth Through Commercialisation of Deep Tech Solutions
 JPMorgan Chase Maintains ACCUMULATE Rating Despite Lower Target Price
 Lion-Phillip S-REIT ETF: Analysts Maintain Positive Outlook Despite Rate Headwinds