Brief Overview
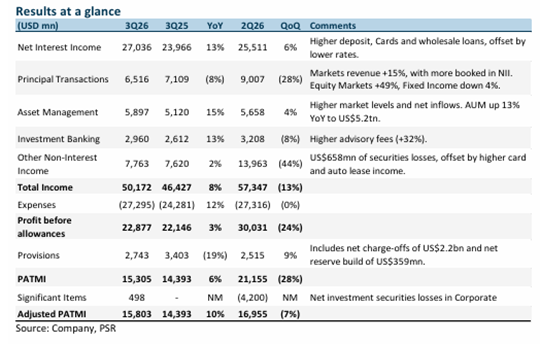
JPMorgan Chase reported 3Q26 adjusted earnings of US$15.8bn, representing a 10% year-on-year increase but falling short of analyst estimates. The performance was impacted by weaker-than-expected Fixed Income trading and investment banking fees, as client activity in Rates, Credit and Commodities weakened following a late September bond sell-off. Despite earnings growth, share buybacks declined significantly to US$1.1bn from US$8.3bn in the prior year, whilst dividends per share increased 10% to US$1.65.
Investment Positives
Prime financing emerged as a key growth driver, significantly boosting Equity Markets performance and Markets net interest income. Equity Markets revenue surged 49% year-on-year to US$5.0bn, driven by Prime and Derivatives activities. This growth expanded the balance sheet substantially, with average Markets interest-earning assets rising 20% year-on-year to US$1.7tn. The yield on these assets improved markedly to 0.57% from 0.19% in 3Q25, propelling Markets NII to US$2.4bn compared to US$0.7bn previously.
The Consumer & Community Banking division delivered strong performance with net income rising 13% year-on-year to US$5.7bn. Card Services & Auto revenue increased 15% year-on-year, supported by 7% card loan growth and an improved card net revenue rate of 10.76% versus 10.03% in 3Q25. Deposit growth remained healthy at 4% year-on-year, bolstered by 650,000 net new checking accounts. Asset management fees rose 15% year-on-year on higher market levels and net inflows.
Credit quality showed improvement with the Card net charge-off rate declining to 2.91% from 3.15%, whilst firmwide net charge-offs fell US$389mn year-on-year due to lower wholesale charge-offs. Management raised FY26 NII guidance to approximately US$106.2bn from US$105.5bn previously, with 2027 central case NII ex-Markets projected at US$107bn.
Challenges
Fixed Income trading faced headwinds with revenue declining 4% due to lower performance in Commodities, Rates and Credit segments. Investment banking deals stalled following the late September bond sell-off, contributing to underperformance relative to expectations. Principal transactions showed weakness, leading to downward revisions in earnings estimates. Adjusted expense guidance was raised to approximately US$108.6bn from US$107.5bn previously, indicating cost pressures.
Outlook
Phillip Securities Research maintains a positive outlook on JPMorgan Chase, highlighting the bank’s earnings diversity and asset-sensitive balance sheet as key strengths. Rate hikes are expected to contribute to NII growth in 2027, with approximately a quarter of projected growth stemming from rate increases. Prime financing and advisory services are positioned to deliver fee growth independent of rate movements. Management’s strategy to redirect capital from buybacks into loans is expected to generate returns exceeding the approximately 6% earnings yield on shares, supporting book value growth into FY27.
Recommendation & Target Price
Phillip Securities Research maintains an ACCUMULATE recommendation for JPMorgan Chase with a revised target price of US$370, reduced from the previous US$380. The target price reduction reflects a 3% decrease in FY26 earnings estimates due to lower principal transactions, asset management and investment banking projections. The valuation assumes 2.93x FY26 price-to-book value and a return on equity estimate of 23.0%.
Frequently Asked Questions
Q: What drove JPMorgan's Equity Markets revenue growth in 3Q26?
A: Equity Markets revenue rose 49% year-on-year to US$5.0bn, primarily driven by Prime and Derivatives activities, with prime financing contributing to significant balance sheet growth.
Q: How did the bank's credit quality perform during the quarter?
A: Credit quality improved with the Card net charge-off rate declining to 2.91% from 3.15% in 3Q25, and firmwide net charge-offs falling US$389mn year-on-year due to lower wholesale charge-offs.
Q: What is JPMorgan's updated guidance for FY26?
A: Management raised FY26 NII guidance to approximately US$106.2bn from US$105.5bn previously, whilst adjusted expense guidance increased to approximately US$108.6bn from US$107.5bn.
Q: Why did Fixed Income trading underperform?
A: Fixed Income revenue fell 4% due to weakened client activity in Rates, Credit and Commodities segments, with investment banking deals stalling after the late September bond sell-off.
Q: What is the bank's outlook for NII growth in 2027?
A: Management's 2027 central case for NII ex-Markets is approximately US$107bn, with about a quarter of the growth expected to come from rate hikes.
Q: How significant was the reduction in share buybacks?
A: Buybacks declined dramatically to US$1.1bn in 3Q26 from US$8.3bn in 3Q25, with management redirecting capital into loans expected to generate higher returns than the share buyback yield.
Q: What factors support the analyst's positive outlook despite the lower target price?
A: The analyst cites JPMorgan's earnings diversity, asset-sensitive balance sheet, rate sensitivity benefits, and prime financing growth as key positives, with capital redeployment from buybacks to loans expected to support book value growth.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.