Brief Overview
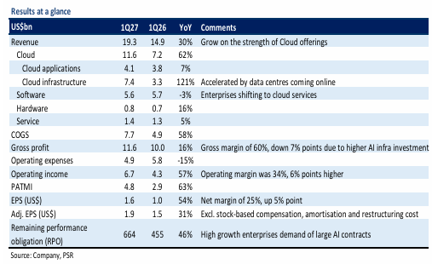
Oracle delivered a solid 1Q27 result that met expectations, with revenue rising 30% year-on-year, driven primarily by strong Cloud Infrastructure growth of 121%. The company expects group revenue to accelerate to 34% growth in FY27, compared to 16% in FY26, as cloud infrastructure deployment continues ramping up. Phillip Securities Research maintains a BUY recommendation whilst reducing the target price to US$225 from US$237.
Investment Positives
Accelerating Cloud Infrastructure Momentum
Oracle Cloud Infrastructure (OCI) revenue growth surged to 121% year-on-year in 1Q27, accelerating from 93% in the previous quarter. The company’s Stargate project is already generating revenue, with 6 of 8 buildings at the Abilene campus now operational, representing 618MW or 75% of planned capacity. This demonstrates that part of the OpenAI project has successfully transitioned from backlog into active revenue generation.
The company’s capacity deployment has accelerated significantly, delivering 850MW of compute capacity and over 300,000 GPUs in the quarter – nearly triple the prior quarter’s deployment pace. This rapid scaling indicates Oracle’s ability to capitalise on the strong AI demand environment.
Strong Demand Visibility Through RPO Growth
Oracle’s remaining performance obligations (RPO) continue to grow robustly, increasing US$26 billion in quarter-on-quarter to US$664 billion, despite the accelerating OCI revenue conversion. This growth pattern indicates that demand remains well ahead of available capacity, positioning Oracle favourably for sustained growth.
The company signed over US$30 billion of new AI contracts in Q1, supported by customer prepayments and alternative financing arrangements. Over the past three quarters, Oracle has secured US$105 billion in bookings under its new funding model, representing 16% of the total RPO. The RPO base is also becoming increasingly diversified, reducing concentration risk from OpenAI as the backlog expands.
Challenges
The report does not explicitly outline specific investment challenges or negative factors affecting Oracle’s business prospects.
Outlook
Oracle expects significant revenue acceleration, with group revenue projected to grow 34% year-on-year in FY27, compared to 16% in FY26. Cloud Infrastructure revenue is forecast to surge 109% to US$38 billion, accounting for 42% of total group revenue. The majority of the US$300 billion OCI commitment is expected to ramp from 2027, whilst a potential IPO could strengthen funding capacity. Earnings are expected to be backloaded into a stronger second half of FY27 on data centre ramp-up.
Recommendation & Target Price
Phillip Securities Research maintains a BUY recommendation for Oracle Corp with a DCF target price of US$225, reduced from the previous target of US$237. The target price reduction reflects a higher share count by approximately 100 million shares following Oracle’s recent At-the-Market equity issuance to fund its aggressive AI infrastructure and data centre expansion.
Frequently Asked Questions
Q: How did Oracle's Cloud Infrastructure perform in 1Q27?
A: Oracle Cloud Infrastructure revenue growth accelerated to 121% year-on-year in 1Q27, up from 93% in the previous quarter, driving overall company revenue growth of 30%.
Q: What is the status of Oracle's Stargate project?
A: Stargate is already being monetised with 6 of 8 buildings at the Abilene campus now operational, representing 618MW or 75% of planned capacity. The remaining two buildings are still under development.
Q: How much new AI contract value did Oracle secure in Q1?
A: Oracle signed over US$30 billion of new AI contracts in Q1, supported by customer prepayments and alternative financing arrangements.
Q: What is Oracle's current remaining performance obligations (RPO)?
A: Oracle's RPO increased by US$26 billion quarter-on-quarter to US$664 billion, indicating strong demand visibility ahead of available capacity.
Q: What revenue growth does Oracle expect for FY27?
A: Oracle expects group revenue to accelerate to 34% year-on-year growth in FY27, compared to 16% in FY26, driven by Cloud Infrastructure revenue surging 109% to US$38 billion.
Q: Why was Oracle's target price reduced despite the BUY recommendation being maintained?
A: The target price was lowered from US$237 to US$225 due to a higher share count by approximately 100 million shares following Oracle's recent At-the-Market equity issuance to fund AI infrastructure expansion.
Q: How much capacity did Oracle deploy in 1Q27?
A: Oracle delivered 850MW of compute capacity and over 300,000 GPUs in 1Q27, nearly triple the prior quarter's deployment pace.
Q: When is the majority of Oracle's OCI commitment expected to ramp up?
A: The majority of the US$300 billion OCI commitment is expected to ramp from 2027.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.