Brief Overview
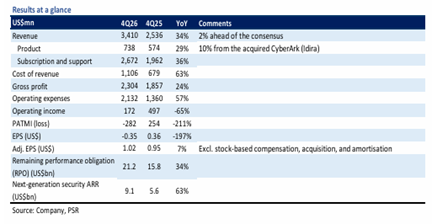
Palo Alto Networks delivered 4Q26 revenue and PATMI results that met expectations, with FY26 results at 101% of forecasts. The company achieved 34% year-on-year revenue growth, driven by platformisation and rising demand for AI-driven security solutions. Future growth is expected to be supported by platformisation, AI infrastructure buildout, and AI security adoption through various offerings.
Investment Positives
Strong organic growth represents a key investment highlight. The company achieved 4Q26 revenue growth of 34.4% year-on-year, marking the strongest performance since 1Q17. This robust growth was underpinned by two primary factors: platformisation, as customers consolidated security spending onto PANW’s platform to reduce costs and complexity, and rising demand for AI-driven security solutions such as Prisma AIRS and Cortex XSIAM (AgentiX) amid escalating AI-related threats.
Platformisation has driven significant upsell and cross-sell opportunities, supporting strong wallet share expansion and sustaining a net retention rate above 120%. The strategy has proven particularly effective among large enterprises, with deals exceeding US$10mn in NGS ARR growing 50% year-on-year in customer count terms. Top deal wins included telecommunications and payment platform companies. NGS refers to PANW’s newest AI- and ML-powered security offerings.
Inorganic growth from acquisitions provides additional momentum. PANW has integrated the financials of two recent acquisitions: CyberArk (Idira), which provides identity security for human, machine, and AI identities, and Chronosphere, which enhances observability across applications, infrastructure, and cloud workloads. Idira contributed US$336mn (10% of 4Q26 revenue) and US$1.5bn (13% of FY26 revenue on a pro forma basis), whilst accelerating 4Q bookings growth. The company also acquired Embrace and Console, though these were immaterial to FY27e guidance.
Challenges
The acquisitions, primarily CyberArk, required funding through a mix of cash and stock, resulting in increased debt levels and higher interest expense. The financing structure also increased shares outstanding in FY27e, which impacts dilution for existing shareholders.
Outlook
Future growth is expected to remain supported by platformisation and AI infrastructure buildout, with over 65% of NGS ARR from platformised customers and over 120% net retention rate supporting upsell and cross-sell activities. Rising AI capital expenditure is driving more infrastructure to secure and traffic to inspect. Additionally, AI security adoption through Prisma AIRS, Cortex, and CyberArk should benefit from autonomous agents increasing demand for governance, identity security and real-time cyber defence.
Recommendation & Target Price
Phillip Securities Research has downgraded its recommendation to NEUTRAL from ACCUMULATE, with a higher DCF-based target price of US$346 (previously US$320). The downgrade follows recent share price performance, with PANW rallying approximately 160% from its February low to an August peak of US$396.
Frequently Asked Questions
Q: What drove Palo Alto Networks' strong revenue performance in 4Q26?
A: Revenue growth of 34.4% year-on-year was driven by platformisation as customers consolidated security spending and rising demand for AI-driven security solutions amid escalating AI-related threats.
Q: How significant was the contribution from recent acquisitions?
A: CyberArk (Idira) contributed US$336mn (10% of 4Q26 revenue) and US$1.5bn (13% of FY26 revenue on a pro forma basis), whilst also accelerating 4Q bookings growth.
Q: What is the company's net retention rate performance?
A: The company maintains a net retention rate above 120%, supported by platformisation-driven upsell and cross-sell opportunities.
Q: How are large enterprise deals performing?
A: Large deals exceeding US$10mn in NGS ARR grew 50% year-on-year in customer count, with top wins including telecommunications and payment platform companies.
Q: What impact did acquisitions have on the company's financial structure?
A: The acquisitions, primarily CyberArk, increased debt levels and interest expense, and also increased shares outstanding in FY27e due to the mix of cash and stock funding.
Q: Why was the recommendation downgraded despite strong performance?
A: The recommendation was downgraded to NEUTRAL from ACCUMULATE following recent share price performance, with PANW rallying approximately 160% from its February low to an August peak.
Q: What are the key growth drivers for FY27e?
A: Growth should be supported by platformisation with over 65% of NGS ARR from platformised customers, AI infrastructure buildout, and AI security adoption through Prisma AIRS, Cortex, and CyberArk.
Q: What does NGS refer to in the context of PANW's offerings?
A: NGS refers to PANW's newest AI- and ML-powered security offerings.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.