Brief Overview
The semiconductor sector has demonstrated mixed performance over the past three months, with the Semiconductor ETF rising 2.4% but underperforming the S&P500’s 4.1% gain. Equipment players faced headwinds due to elevated valuations, while memory companies declined amid HBM4 shipment uncertainties. However, enterprise and sovereign AI buildout is driving higher demand, with Coreweave and Nebius’ combined remaining performance obligations reaching US$141 billion in June 2026.
Investment Positives
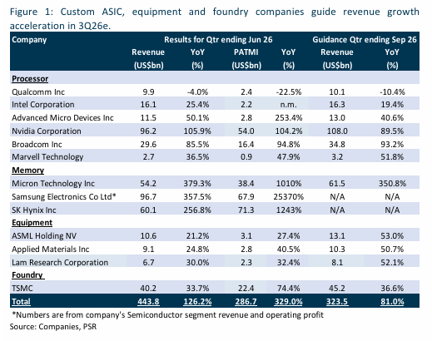
The semiconductor sector presents compelling growth opportunities across multiple segments. Custom ASIC companies are leading the acceleration, with Broadcom and Marvell guiding 3Q26e revenue to surge 89% year-on-year to a combined US$38 billion, surpassing the combined growth guidance of 83% from NVIDIA and AMD.
Equipment manufacturers are experiencing robust demand, with their combined 3Q26e revenue guided to reach 52% year-on-year growth to US$31.4 billion, representing potentially the largest growth since 2021. This equipment demand is underpinned by TSMC’s increased capital expenditure guidance of US$62 billion, marking a 15% increase, alongside memory players’ higher equipment spending as new fabrication facilities ramp up production.
The broadening customer base strengthens the sector’s resilience. Coreweave and Nebius have expanded their client roster to include major enterprises such as Caterpillar, Grammarly, Databricks, Reflection, AI neolabs and quantitative trading firms. This diversification across AI neoclouds, enterprises and sovereign nations makes NVIDIA and AMD’s growth more resilient should hyperscaler capital expenditure moderate.
From a valuation perspective, large-cap SaaS companies are trading at roughly -1 standard deviation, with an EV/Sales multiple of 9.5x versus their 3-year average of 10.8x, suggesting attractive valuations despite strong performance.
Enterprise and sovereign nations’ AI buildout continues to drive substantial demand growth, with Coreweave and Nebius’ combined remaining performance obligations increasing 72% from December 2025 to reach US$141 billion by June 2026.
Challenges
Valuation concerns persist in certain segments of the semiconductor sector. Equipment players AMAT and Lam Research have experienced significant pullbacks, declining 10.6% and 3.7% respectively, as they trade at elevated forward price-to-earnings ratios of 40x and 34x, compared with the sector average of 27x.
Memory companies face headwinds from currency fluctuations and product transition uncertainties. SK Hynix declined 17% while Samsung fell 1.9%, laregly due to uncertainty surrounding HBM4 shipment timelines and the impact of a stronger Korean won on their financial performance.
Outlook
The outlook for the semiconductor sector remains positive, supported by accelerating growth across the custom ASIC, equipment and foundry segments. Revenue growth acceleration is expected in 3Q26e across these key areas, with custom ASIC companies leading the charge. The diversification of AI demand across multiple customer segments provides additional stability to the growth trajectory.
Recommendation & Target Price
Phillip Securities Research maintains an OVERWEIGHT recommendation on the semiconductor sector, reflecting confidence in the strong growth momentum of custom ASIC companies, equipment manufacturers and foundry operations.
Frequently Asked Questions
Q: Which semiconductor segments are showing the strongest growth acceleration?
A: Custom ASIC companies are leading growth, with Broadcom and Marvell guiding 3Q26e revenue to accelerate 89% year-on-year to US$38 billion, followed by equipment players expecting 52% year-on-year growth.
Q: What is driving the equipment sector's strong performance?
A: Equipment demand is supported by TSMC's 15% higher capex guidance to US$62 billion and memory players' increased equipment spending as new fabrication facilities ramp up production.
Q: How has customer diversification benefited semiconductor companies?
A: GPU demand is broadening across AI neoclouds, enterprises and sovereign nations, making NVIDIA’s and AMD's growth more resilient if hyperscaler capex moderates. New customers include Caterpillar, Grammarly, Databricks and quantitative trading firms.
Q: What challenges are equipment companies facing?
A: AMAT declined 10.6% and Lam fell 3.7% as they trade at elevated valuations of 40x and 34x forward P/E respectively, compared with peers' average of 27x.
Q: Why have memory companies underperformed?
A: SK Hynix declined 17% and Samsung fell 1.9% due to uncertainty in HBM4 shipment timeline and a stronger Korean won impacting their performance.
Q: How significant is the AI buildout demand?
A: Coreweave and Nebius' combined remaining performance obligations reached US$141 billion in June 2026, representing a 72% increase from December 2025.
Q: What is the overall sector recommendation?
A: Phillip Securities Research maintains an OVERWEIGHT recommendation on the semiconductor sector based on strong growth acceleration across custom ASIC, equipment and foundry segments.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.