Raffles Edu - Stock Analyst Research
| Target Price* | 0.20 |
| Recommendation | BUY› BUY |
| Market Cap* | - |
| Publication Date | 16 Oct 2026 |
*At the time of publication
Raffles Education Ltd - Back to school and growth
- Returning to net cash through asset monetisations, Raffles Education (RE) will focus on growing its K-12 presence in ASEAN. The increasing regionalisation of higher education within ASEAN, driven by easing immigration policies within Asia and restrictive immigration policies in the UK and US, will support RE’s expansion.
- RE is growing its K-12 platforms in Thailand (RAS Bangkok expansion), Malaysia (RAS Iskandar) and Indonesia (new K-12 school in Jakarta). To fund this growth and further deleverage, we estimate RE’s planned asset sales yielding over S$500mn of gross proceeds (Figure 1). Divesting these lower-return China assets (revenue return on non-current assets: China 9% vs ASEAN 22%) would improve group asset efficiency.
- We initiate coverage on Raffles Education with a BUY rating and target price of S$0.20. Our valuation is based on DCF analysis, using a 7% WACC and a 7.5x EV/EBITDA exit multiple based on peer comparables. Our TP is conservative, as our share count reflects dilution from warrants, and takes into account c. S$35mn of resulting cash proceeds. RE currently trades at c.11x FY27e EV/EBITDA. It is expected to be in a net cash position by FY27/28.
Company Background
• RE is a Singapore-listed private education group. Founded in 1990, it runs 13 institutions
(K-12 schools, universities and design colleges) across eight countries, with c.12,400
students. ASEAN is its core market, contributing 57% of FY26 course fees. It owns 75% of
HK-listed Oriental University City Holdings (OUCHK), a consolidated subsidiary that leases
out a college campus in Langfang, China.
Investment Thesis
+ Strengthening presence in ASEAN region. Raffles Education is expanding its Kk-12
education presence through Malaysia, Thailand and Indonesia (Figure 2). We believe RE is
well placed to benefit from i) increasing regionalisation of higher education within Asia, ii)
expanding base of affluent locals that drive demand for international schools. Visa
restrictions, rising tuition fees, and policy uncertainty in the US and UK will drive outbound
Asia demand away from the US/UK back toward the ASEAN region. Enrolment trends are
strong, with Raffles University enrolment more than doubling from 438 students in 2022 to
1,002 in 2025 (Figure 3).
+ Disposing lower return assets. In FY26, Raffles Education sold 51 Merchant Road,
Singapore, for S$121.8mn (a S$52.3mn gain) and Wanbo College, Hefei, for S$78.4mn (a
S$29.4mn loss). We expect more assets to be divested (Figure 1), worth more than c.
S$500mn in gross proceeds before tax deductions. The majority of the lower-return assets
are either vacant land or assets located in China (FY26 revenue per dollar of non-current
assets: ASEAN 0.22x vs China 0.09x). Education stocks listed in China trade at a median P/E of
1.9x vs 11.1x for SEA peers (Figure 4). Exiting low-return China assets makes RE a more ASEAN
focused business, which could narrow its valuation gap to SEA peers.
+ Anchored by local demand, lifted by regional investment. Most of RE’s assets rely on
affluent local demand except Raffles Singapore and RAS Iskandar, which rely on expatriates
(Figure 5). We believe increased investment in SEA will have a knock-on effect by expanding
the base of affluent locals. The RTS link and the Johor-Singapore Special Economic Zone in
Malaysia/Singapore, the Eastern Economic Corridor (EEC) special economic zone in Thailand,
and the Belt and Road project benefiting Indonesia will be key drivers of jobs and inward
investment, adding to demand for international schooling.
About the author
Hashim Osman
Research Analyst
PSR
Hashim graduated from the National University of Singapore with a degree in Business Administration.
Important Information
This report is prepared and/or distributed by Phillip Securities Research Pte Ltd ("Phillip Securities Research"), which is a holder of a financial adviser’s licence under the Financial Advisers Act, Chapter 110 in Singapore.
By receiving or reading this report, you agree to be bound by the terms and limitations set out below. Any failure to comply with these terms and limitations may constitute a violation of law. This report has been provided to you for personal use only and shall not be reproduced, distributed or published by you in whole or in part, for any purpose. If you have received this report by mistake, please delete or destroy it, and notify the sender immediately.
The information and any analysis, forecasts, projections, expectations and opinions (collectively, the “Research”) contained in this report has been obtained from public sources which Phillip Securities Research believes to be reliable. However, Phillip Securities Research does not make any representation or warranty, express or implied that such information or Research is accurate, complete or appropriate or should be relied upon as such. Any such information or Research contained in this report is subject to change, and Phillip Securities Research shall not have any responsibility to maintain or update the information or Research made available or to supply any corrections, updates or releases in connection therewith.
Any opinions, forecasts, assumptions, estimates, valuations and prices contained in this report are as of the date indicated and are subject to change at any time without prior notice. Past performance of any product referred to in this report is not indicative of future results.
This report does not constitute, and should not be used as a substitute for, tax, legal or investment advice. This report should not be relied upon exclusively or as authoritative, without further being subject to the recipient’s own independent verification and exercise of judgment. The fact that this report has been made available constitutes neither a recommendation to enter into a particular transaction, nor a representation that any product described in this report is suitable or appropriate for the recipient. Recipients should be aware that many of the products, which may be described in this report involve significant risks and may not be suitable for all investors, and that any decision to enter into transactions involving such products should not be made, unless all such risks are understood and an independent determination has been made that such transactions would be appropriate. Any discussion of the risks contained herein with respect to any product should not be considered to be a disclosure of all risks or a complete discussion of such risks.
Nothing in this report shall be construed to be an offer or solicitation for the purchase or sale of any product. Any decision to purchase any product mentioned in this report should take into account existing public information, including any registered prospectus in respect of such product.
Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report, may provide an array of financial services to a large number of corporations in Singapore and worldwide, including but not limited to commercial / investment banking activities (including sponsorship, financial advisory or underwriting activities), brokerage or securities trading activities. Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report, may have participated in or invested in transactions with the issuer(s) of the securities mentioned in this report, and may have performed services for or solicited business from such issuers. Additionally, Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report, may have provided advice or investment services to such companies and investments or related investments, as may be mentioned in this report.
Phillip Securities Research or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report may, from time to time maintain a long or short position in securities referred to herein, or in related futures or options, purchase or sell, make a market in, or engage in any other transaction involving such securities, and earn brokerage or other compensation in respect of the foregoing. Investments will be denominated in various currencies including US dollars and Euro and thus will be subject to any fluctuation in exchange rates between US dollars and Euro or foreign currencies and the currency of your own jurisdiction. Such fluctuations may have an adverse effect on the value, price or income return of the investment.
To the extent permitted by law, Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report, may at any time engage in any of the above activities as set out above or otherwise hold an interest, whether material or not, in respect of companies and investments or related investments, which may be mentioned in this report. Accordingly, information may be available to Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report, which is not reflected in this report, and Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited to its officers, directors, employees or persons involved in the issuance of this report, may, to the extent permitted by law, have acted upon or used the information prior to or immediately following its publication. Phillip Securities Research, or persons associated with or connected to Phillip Securities Research, including but not limited its officers, directors, employees or persons involved in the issuance of this report, may have issued other material that is inconsistent with, or reach different conclusions from, the contents of this report.
The information, tools and material presented herein are not directed, intended for distribution to or use by, any person or entity in any jurisdiction or country where such distribution, publication, availability or use would be contrary to the applicable law or regulation or which would subject Phillip Securities Research to any registration or licensing or other requirement, or penalty for contravention of such requirements within such jurisdiction.
This report is intended for general circulation only and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. The products mentioned in this report may not be suitable for all investors and a person receiving or reading this report should seek advice from a professional and financial adviser regarding the legal, business, financial, tax and other aspects including the suitability of such products, taking into account the specific investment objectives, financial situation or particular needs of that person, before making a commitment to invest in any of such products.
This report is not intended for distribution, publication to or use by any person in any jurisdiction outside of Singapore or any other jurisdiction as Phillip Securities Research may determine in its absolute discretion.
IMPORTANT DISCLOSURES FOR INCLUDED RESEARCH ANALYSES OR REPORTS OF FOREIGN RESEARCH HOUSE
Where the report contains research analyses or reports from a foreign research house, please note:
- recipients of the analyses or reports are to contact Phillip Securities Research (and not the relevant foreign research house) in Singapore at 250 North Bridge Road, #06-00 Raffles City Tower, Singapore 179101, telephone number +65 6533 6001, in respect of any matters arising from, or in connection with, the analyses or reports; and
- to the extent that the analyses or reports are delivered to and intended to be received by any person in Singapore who is not an accredited investor, expert investor or institutional investor, Phillip Securities Research accepts legal responsibility for the contents of the analyses or reports.
About the author
Hashim Osman
Research Analyst
PSR
Hashim graduated from the National University of Singapore with a degree in Business Administration.
 Wells Fargo & Company – Loan growth and cost cuts lift EPS 13%
 JPMorgan Chase & Co – NII guidance raised; buybacks cut
 Nanofilm Technologies International Limited - Deep Tech to Money Tech
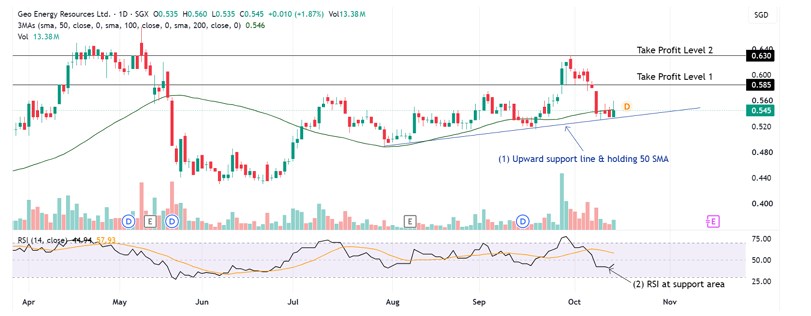 Trade of The Day - Geo Energy Resources Ltd (SGX: RE4)