ETF Monthly Review: Mixed September Performance with Muted October Outlook Expected October 8, 2026
Brief Overview
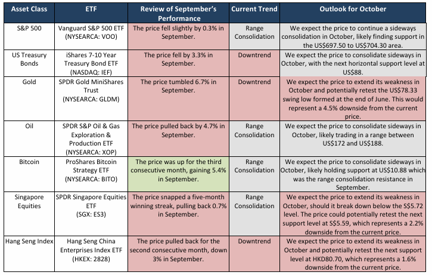
September proved challenging for most ETFs, with the gold-tracking ETF (GLDM) suffering the steepest decline of 6.7%, whilst the Bitcoin ETF (BITO) stood as the sole gainer with a 5.4% rise. Current market conditions show most major asset classes in range consolidation, though US Treasury Bonds, Gold, and the Hang Seng Index remain in downtrends. October is anticipated to bring sideways consolidation for some assets whilst others may extend their weakness.
Investment Positives
Limited bright spots emerged from September’s performance, with Bitcoin demonstrating notable resilience. The ProShares Bitcoin Strategy ETF gained 5.4% in September, marking its third consecutive month of positive performance. This sustained momentum reflects continued strength in the cryptocurrency space despite broader market challenges.
The S&P 500 showed relative stability, with the Vanguard S&P 500 ETF experiencing only a modest 0.3% decline during September. This minimal pullback suggests underlying market resilience in US equities, with the index maintaining its position within a range consolidation pattern.
Several ETFs are positioned for sideways consolidation in October, indicating potential stability ahead. The S&P 500 ETF is expected to find support in the US$697.50 to US$704.30 area, whilst the oil-focused XOP ETF may trade within a defined range between US$172 and US$185.
Challenges
Gold faced significant headwinds in September, with the SPDR Gold MiniShares Trust tumbling 6.7% to become the month’s worst performer. The precious metal has entered a clear downtrend, raising concerns about further weakness ahead.
US Treasury Bonds encountered notable pressure, with the iShares 7-10 Year Treasury Bond ETF declining 3.3% in September. This asset class has shifted into a downtrend pattern, reflecting challenging conditions in the fixed income market.
Asian markets demonstrated vulnerability, with the Hang Seng China Enterprises Index ETF pulling back 3% for the second consecutive month, maintaining its downtrend status. Singapore Equities also showed weakness, with the relevant ETF snapping a five-month winning streak by declining 0.7%.
Oil markets faced headwinds with the SPDR S&P Oil & Gas Exploration & Production ETF pulling back 4.7% during September, though it remains within a range consolidation pattern.
Outlook
October is expected to deliver muted performance across most asset classes. Four major ETFs – those tracking the S&P 500, US Treasury Bonds, Oil, and Bitcoin – are anticipated to consolidate sideways during the month.
However, three asset classes face potential further weakness. Gold may extend its decline and potentially retest the US$78.33 swing low from late June, representing a 4.5% downside risk. Singapore Equities could fall to the US$5.59 support level if they break below US$5.72, indicating a possible 2.2% decline. The Hang Seng Index may retest support at HK$80.70, suggesting a potential 1.6% downside.
Recommendation & Target Price
The report provides specific technical levels and percentage projections for various ETFs but does not include an overall investment recommendation or target prices. The analysis focuses on directional expectations, with some assets expected to consolidate whilst others may extend their current weakness into October.
Frequently Asked Questions
Q: Which ETF performed worst in September 2026?
A: The SPDR Gold MiniShares Trust (GLDM) was the worst performer, tumbling 6.7% during September.
Q: What was the only ETF to gain in September?
A: The ProShares Bitcoin Strategy ETF (BITO) was the sole gainer, rising 5.4% and marking its third consecutive month of gains.
Q: Which asset classes are currently in downtrends?
A: US Treasury Bonds, Gold, and the Hang Seng Index are all currently experiencing downtrend patterns.
Q: What is the outlook for Gold in October?
A: Gold is expected to extend its weakness and potentially retest the US$78.33 swing low from late June, representing a 4.5% downside from current levels.
Q: How did the S&P 500 perform in September?
A: The Vanguard S&P 500 ETF fell slightly by 0.3% in September and is currently in a range consolidation pattern.
Q: Which ETFs are expected to consolidate sideways in October?
A: The ETFs tracking the S&P 500, US Treasury Bonds, Oil, and Bitcoin are expected to consolidate sideways during October.
Q: What support level is anticipated for Singapore Equities?
A: If Singapore Equities break below the US$5.72 level, they could potentially retest the next support level at US$5.59, representing a 2.2% downside.
Q: How did Asian markets perform in September?
A: Asian markets showed weakness, with the Hang Seng China Enterprises Index ETF down 3% for the second consecutive month and Singapore Equities declining 0.7%, ending a five-month winning streak.
This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst.
Disclaimer
These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products.
Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance.
Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries.
The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries.
Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned.
This advertisement has not been reviewed by the Monetary Authority of Singapore.
About the author
Zane Aw
Zane Aw is an equity research analyst focused on technical analysis, covering the Singapore, Hong Kong and United States markets. He applied a rules-based approach that incorporate trend-following techniques, price action, momentum oscillators and other indicators to anticipate key inflection points in individual stocks, sectors and broader indices. He graduated from Nanyang Technological University with a Bachelor of Accountancy (Honours).
 Investing in the AI Revolution: A Guide to Semiconductor & Ecosystem ETFs
 Phillip SING Income ETF Reaches All-Time High Dividend with Banking Sector Focus
 Understanding Emerging Markets ETFs
 Suntec REIT Shows Strong Singapore Performance with 24.8% DPU Growth, ACCUMULATE Rating and S$1.69 Target Price