News & Research
Hear from the Experts
Market Overview
*15mins delayed
| 6 November 2026
Recent Podcasts:
Microsoft: Azure Grows 48%. Can Returns Keep Pace With Soaring AI Spending?
Spotify: Revenue Up 16% on Pricing Power. Can AI Become a Growth Lever?
Netflix: Viewing Hours Grow Just 2%. Can Price Hikes and Ads Revive Growth?
Trades Initiated in Past Week
Singapore stocks ended higher on Thursday. The benchmark index gained 0.5% or 27.62 points to finish at 5,296.25.
Stocks plummeted on Thursday as investors accelerated their move away from technology stocks on fears of a data-center buildout slowdown. The Nasdaq Composite declined 5.52% to close at 24,315.00. The tech-heavy index slid into correction territory, falling more than 10% below a record set last month. The S&P 500 dropped 4.36% to end at 7,353.73. The Dow Jones Industrial Average shed 1,833.06 points, or 3.44%, and settled at 51,523.06.
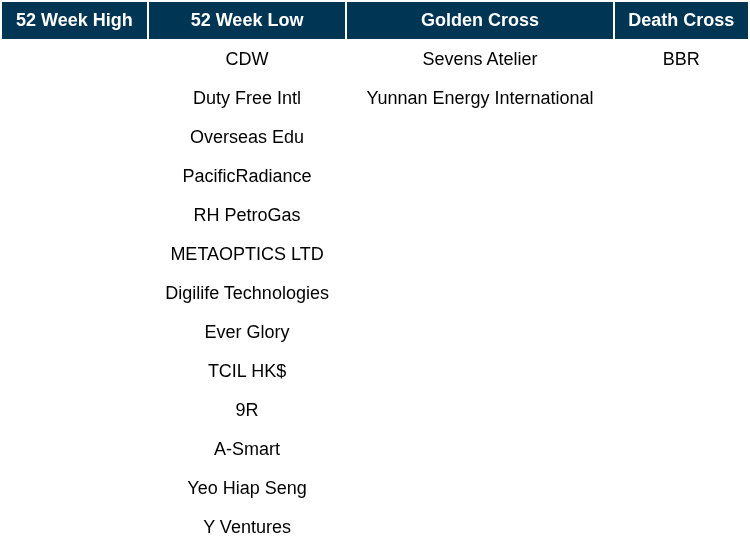
Singapore Technical Highlights
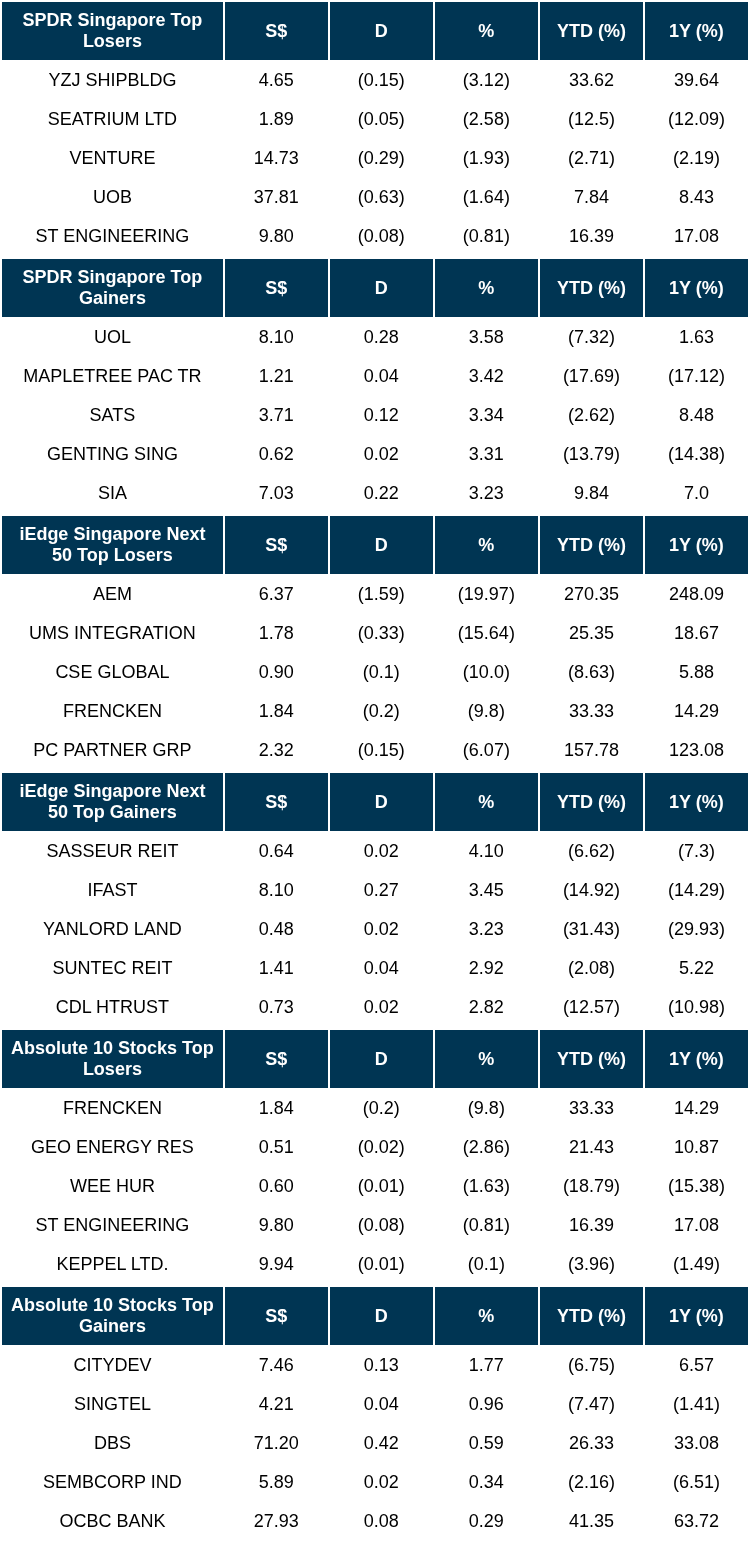
TOP 5 GAINERS & LOSERS
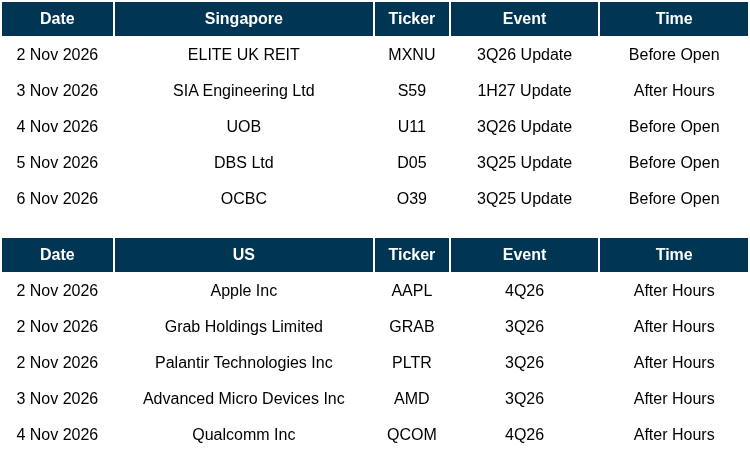
EVENTS OF THE WEEK
SG
OCBC’s 3Q26 earnings of S$2.04bn (+3% YoY) missed our estimates, with 9M26 at 70% of our FY26e forecast. The miss came from Great Eastern. Mark-to-market losses on its bond portfolio as rates rose cut insurance income 37% YoY and trading income 10% YoY. Banking operations profit rose 16% YoY to a record S$1.90bn. NII rose 4% YoY to S$2.31bn, a six-quarter high, as 15% average asset growth offset an 18bps YoY fall in NIM to 1.66%. Higher US rates lifted funding costs faster than asset yields this quarter, which management expects to reverse as assets reprice. Customer flow trading income hit a record S$480mn (+29% YoY), and fees rose 8% YoY. Allowances fell 63% YoY to S$52mn (credit cost 6bps), and the NPL ratio improved to 0.8%. Management raised FY26e loan growth guidance to low-double-digit (prev. high-single to low-double-digit) and will complete the S$2.5bn capital return by FY26.
Glenn Thum
Research Manager
AvePoint Q3 update: ARR up 27%, record net adds, FY guide raised.
SingPost H1 underlying profit doubles to S$11.5m; parcels offset mail.
Starhill Global REIT’s anchor tenant at David Jones Building enters voluntary administration, potential DPU impact.
Thakral leases 3.5 acres of its 21-acre Gurugram site to Manipal Health Enterprise for hospital development.
TOTM Technologies forms joint venture with ClaudeLabs to deliver AI consultancy, implementation and integration services.
US
Nvidia partner Foxconn sales up 46% on AI demand.
Micron said to pause work on US$4.5bn Taiwan plant after labour spat.
Anthropic faces valuation pushback on $1.5T IPO following market rout, WSJ reports.
Lyft to expand Waymo robotaxi fleet in Nashville by year-end.
Airbnb lifts annual revenue growth forecast on resilient global travel demand.
Google plans $17 billion Wyoming data center amid rising threats of curbs.
Source: SGX Masnet, Bloomberg, Channel NewsAsia, Reuters, CNBC, WSJ, The Business Times, The Edge Singapore, PSR
RESEARCH REPORTS
DBS Group Holdings Ltd – Deposit gains lift NIM as trading fees fall
Recommendation: ACCUMULATE; TP S$76.00; Last close: S$71.20; Analyst Glenn Thum
- 3Q26 earnings of S$2.8bn were slightly below our estimates, with 9M26 at 71% of our FY26e forecast on lower-than-expected markets trading and wealth fees. Weaker Asian equity markets and a late-September rise in rates dampened trading volumes, and clients slowed purchases of equity-structured products. 3Q26 DPS rose 8% YoY to 81 cents (66 cents ordinary, 15 cents capital return).
- NII rose 4% YoY as loan growth, led by non-trade corporate lending, and hedging offset lower SORA. Exit NIM rose to 1.90% (2Q26: 1.87%) after SORA turned up in September, and management says NII is past its trough. Treasury customer sales rose 15% YoY on higher sales to wealth and institutional clients. For FY27e, DBS guides mid-single-digit total income growth, NII growth close to 5%, a low-40% CIR and SP of 17-20bps.
- Maintain ACCUMULATE with a lower target price of S$76.00 (prev. S$85.00) as we lower FY26e earnings by 4% from lower NII and trading income estimates. We assume a 3.04x FY26e P/BV and a 17.5% ROE estimate in our GGM valuation. DBS remains our top pick among the three local banks. It has the highest ROE (FY26e ROE: DBS: 17.5%, OCBC: 14.3%, UOB: 10.7%), and its NIM is rising while UOB’s falls (exit NIM: DBS: 1.90%, UOB: 1.64%). DBS held deposit rates up earlier in the year and has won deposit share for two quarters. Record net new money builds the base for wealth fees. The 4.6% FY26e yield is above UOB’s 4.2%, with the 15 cents capital return committed to end-2027.
Phillip Singapore Monthly: November 2026 – AI indigestion
Analyst: Paul Chew
- Singapore equities endured a difficult month. The 5.3% pullback was the steepest monthly drop since the 17% rout in March 2020. Cyclicals and commodities bore the brunt of the de-risking, alongside retreating banks. Conversely, Jardine Group counters led gainers. The Next50 mid-cap index shed 7%, while REITs were resilient, easing just 1%.
- De-risking across AI exposures has weighed on global cyclicals. The spike in AI equity and debt issuance has pushed investors to reduce their concentration in this sector. Semiconductor stocks have corrected 15%, while credit default spreads and borrowing costs have risen sharply. Nevertheless, memory prices or GPU lease rates do not reveal any tapering in infrastructure demand. We believe the AI adoption cycle is in its infancy, with physical infrastructure still being built out. Hard to be an AI train wreck if it is so well telegraphed.
- We remain positive on cyclicals, specifically semiconductors and commodities. Their multiples have de-rated, but the earnings growth remains intact. The unwinding of the AI trade has capped interest rates. But the risk of another rate hike in December remains. Banks offer pricing power as interest rates firm up, with volume growth from loan expansion of 13%.
SIA Engineering Co. Ltd – SAESL drag will near its peak
Recommendation: BUY; TP S$3.76; Last close: S$2.92; Analyst Hashim Osman
- 2Q27/1H27 PATMI was largely stable, +3.0%/-1.7% YoY to S$41.6mn/S$81.9mn, and forming 23%/45% of our full year FY27e estimate. However, revenue fell 10.7%/9.7% YoY to S$331.0mn/S$658.6mn on lower pass-through materials revenue attributed to the mix of work performed (fewer material-intensive heavy checks: 37 in 1H27 vs 44 in 1H26)
- Associates’ income increased 19% YoY to S$62.6mn in 1H27, attributable to Eagle Services Asia (ESA), which works on GTF engines. JV income collapsed 94% to S$1mn, due to SAESL expansion costs (staff expenses, consultancy fees, and interest expense on debt taken to fund the expansion). JV costs are expected to taper by the end of FY27/28.
- We maintain BUY with lower TP of S$3.76 (prev: S$3.90). FY27e PATMI is reduced by 3.3%, as we update our SAESL cost assumptions. 2H27e performance should benefit from easing start-up losses at BMM, whose first hangar is now at full capacity. Management does not expect gestation costs to rise when the second hangar arrives by year-end. SAESL’s expansion costs peak in FY26/27, with early revenue from the Seletar site and some cost tapering by year-end offering partial gestation relief. SIA Engineering is trading at a FY27e P/E of 18.6x (below peer comps FY27e P/E of 23.8x).
Market Journal articles powered by PhillipGPT
First REIT: Accumulate With a Lower Target Price of S$0.17 — Still Waiting for the Next Move
Tesla Q3 2026 Results: Margin Recovery and SELL Rating Outlook
Netflix Inc: Viewing Time a Big Concern — Target Price US$100
PSR Stocks Coverage
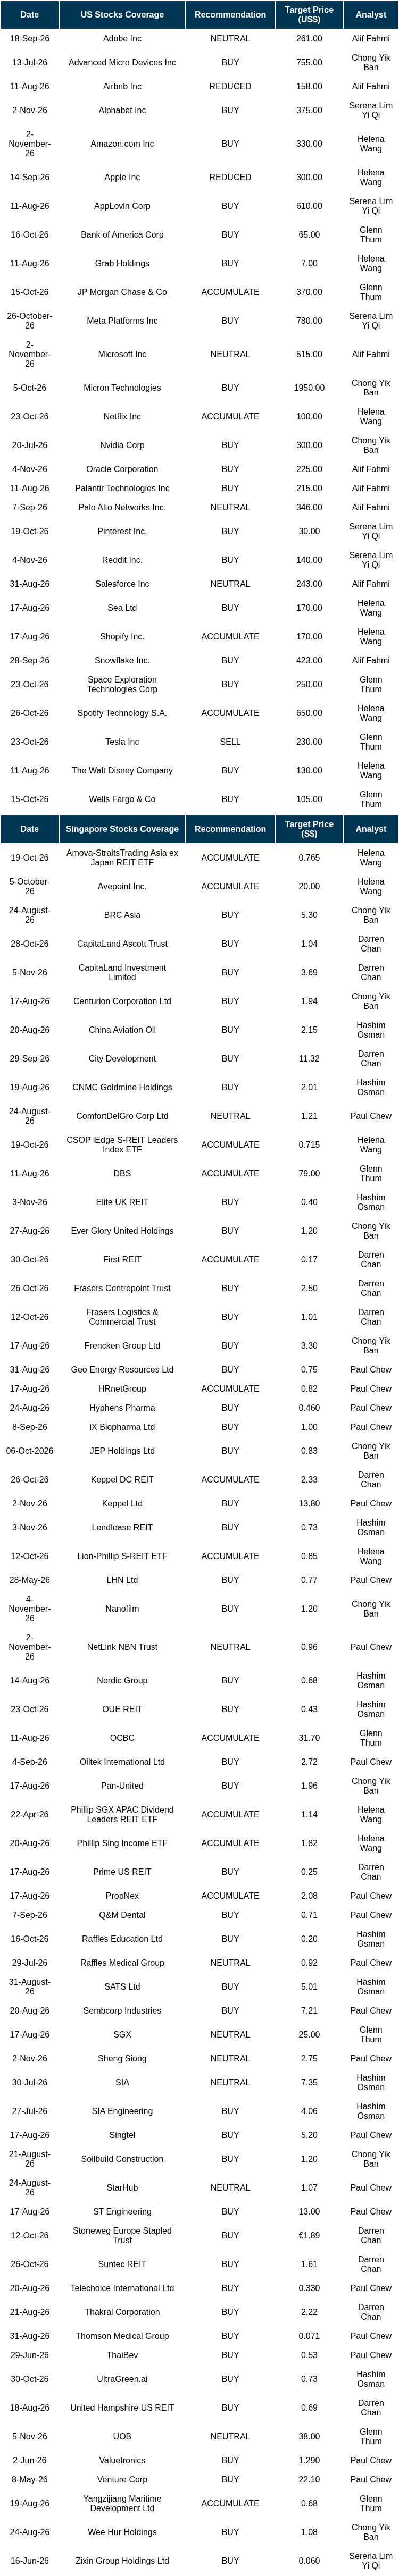
For more information, please visit:
https://www.stocksbnb.com/singapore-stocks-coverage/
HK Reports
Read up on our Hong Kong reports here
Upcoming Webinars
Corporate Insights by AvePoint
Date & Time: 11 November 26 | 9PM-10PM
Register: poems-20261111-158923
Corporate Insights by Sasseur REIT [NEW]
Date & Time: 17 November 26 | 12PM-1PM
Register: poems-20261117-159082
Corporate Insights by Uni-Asia Group Limited
Date & Time: 25 November 26 | 12PM-1PM
Register: poems-20261125-158929
POEMS Podcast:
Research Videos
Weekly Market Outlook: GOOGL, MSFT, AMZN, Sheng Siong, Keppel, Tech Analysis & More!
Date: 2 November 2026Click here for more on Market Outlook.
Sign up for our webinars here, and be among the first to receive economy and market updates.