Trade sizing
Table of Contents
Trade sizing
In order to manage risk, maximise profits, and accomplish long-term trading goals, it is essential to master the skill of allocating the right amount of money to a transaction. Successful trading requires careful consideration of trade sizing. It is frequently overlooked, despite the fact that it may build or destroy a trader’s career, while many traders concentrate on entry and exit tactics.
What is trade sizing?
Determining the amount of capital to invest in a single trade is known as trade size. It’s not a one-size-fits-all strategy; rather, it calls for careful thought and modification based on a number of aspects. These variables include the trader’s risk tolerance, market circumstances, account size, as well as a specific trading approach.
Understanding trade sizing
The right trade size aids investors and traders in managing possible losses and maximising gains. Risk tolerance, account size, anticipated volatility, and the particular trading method being used are all variables that affect trade sizing. Individuals may achieve a balance between profit potential and capital preservation by properly sizing deals, ensuring that no one trade has an unfavourable effect on their whole portfolio. Maintaining financial security and long-term trading success depend on this practice.
Trading professionals may better manage risk, retain emotional control, and increase their prospects of long-term success in financial markets by implementing strong risk management concepts and sticking to well-defined trade size techniques. Always keep in mind that your ability to conserve and develop your trading money over time is more important than simply how much you may profit from a single deal.
Working of trade sizing
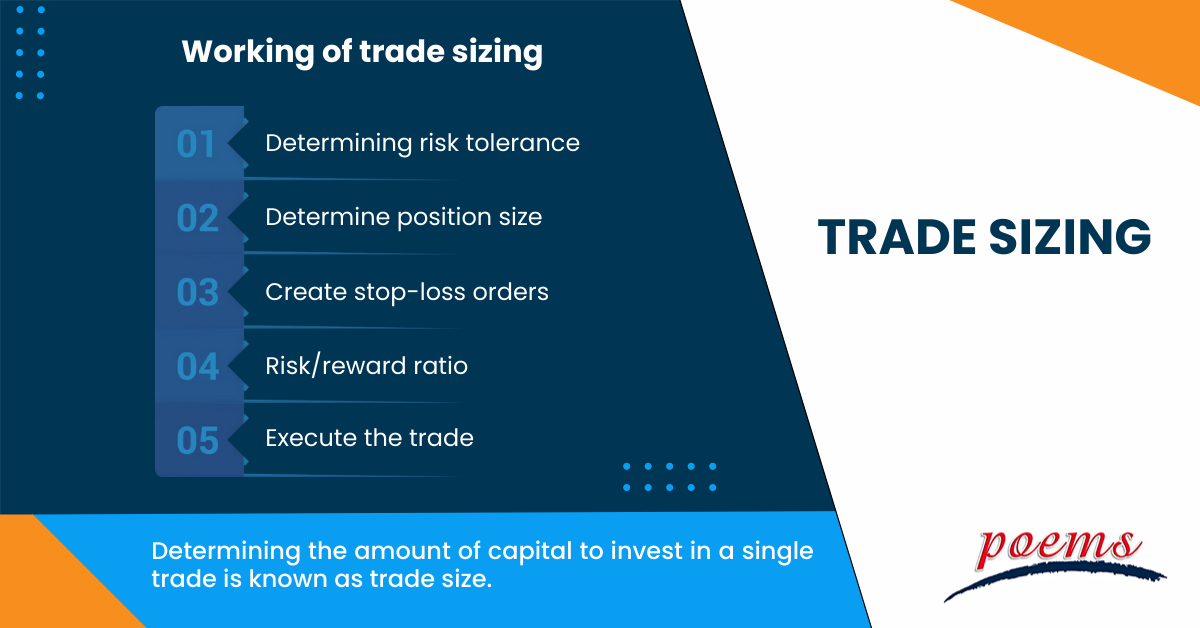
In simple words, here’s how trade sizing works:
- Determining risk tolerance
Traders must first assess their level of risk tolerance. Knowing how much of their cash they are prepared to risk on a single deal is essential for this. Risk tolerance varies from person to person and is influenced by things like experience, financial objectives, and psychological fortitude.
- Determine position size
Traders utilise their defined risk tolerance to determine the position size for a transaction. This entails figuring out how much money will be at stake in the deal, often expressed as a percentage of the entire trading capital.
- Create stop-loss orders
For every trade, traders need to specify a stop-loss order. The stop-loss is a pre-set price level below which the deal will be closed off in order to prevent further losses. The separation between the entry point and the stop-loss level influences the position size.
- Risk/reward ratio
Traders weigh the risk vs the potential profit. They seek a favourable risk-reward ratio in which the possibility of profit outweighs the possibility of loss.
- Execute the trade
The trader completes the transaction having established the position size and risk criteria. This entails entering the market at a particular price, and the size of the position guarantees that the calculated risk remains intact.
Importance of trade sizing
Trade size is crucial in both trading and investing. Risk management, long-term viability and profitability are all directly influenced. Effective trade sizing benefits traders in different ways.
- Risk management reduces the chances of major losses by ensuring that no single deal poses a significant danger to a trader’s capital.
- Proper trade size lessens the emotional stress related to trading since it limits losses and discourages overtrading.
- Traders that keep their trade sizes constant might create a better organised and long-lasting trading approach.
- Profits may be maximised by traders using smart capital allocation techniques when pricing trades.
Examples of trade sizing
For instance, if a trader wishes to purchase shares of a stock with a 5% maximum risk per transaction and has a US$100,000 portfolio, they might allocate US$5,000 (US$100,000 * 0.05) to that trade. This would be equivalent to buying 100 shares of the stock at US$50 a share. The right trade size guarantees that any losses are controllable and complement the investor’s entire risk management plan.
Frequently Asked Questions
You must take into account your risk tolerance, account balance, and the particulars of the trade when determining trade size. Utilising a portion of your whole account balance is a frequent strategy.
Here is an easy formula: trade size = stop loss in pips / (account balance * risk percentage).
Calculating the right amount of capital to allocate to each transaction or investment is known as capital sizing in trading. It is an essential risk management technique that aids traders and investors in safeguarding their investments. Setting a maximum proportion of total money that can be staked on a single deal aims to minimise excessive losses and maximise rewards.
The risk tolerance of the trader, the volatility of the asset, and the diversification of the entire portfolio all influence this proportion, also known as position size. The markets are more likely to be sustainable over the long run when capital is appropriately sized to guarantee that no single deal has the potential to have a substantial influence on the trader’s overall financial health.
As it directly affects risk and possible profits, trade size is important in both investing and trading. A larger trade size suggests more exposure to market volatility, which might result in both larger gains and losses.
Smaller trade sizes, on the other hand, lower risk but may restrict possible gains. Your risk tolerance, financial objectives, and portfolio diversification should influence your trade size selections.
Effective trade size management allows you to protect money, follow your risk management plan, and strike a balance between the likelihood of profit and the likelihood of loss, assisting you in maintaining a profitable and long-lasting trading or investing strategy.
A risk management principle known as the “3-5-7” rule in trading advises diversifying one’s financial holdings to reduce risk.
- 3% rule
The 3% rule states that you should never risk more than 3% of your whole trading capital on a single deal. In order to safeguard themselves against big losses, traders attempt to restrict exposures on a single deal.
- 5% rule
According to the second element, you shouldn’t put more than 5% of your total trading capital at risk in the market at any given moment. This takes into consideration numerous holdings and helps avoid very high market or asset concentration.
- 7% rule
The final part states that your portfolio’s overall maximum loss should be at most 7% of your trading capital. This regulation emphasises the significance of placing stop-loss orders to reduce possible losses.
To trade using position size, you must first choose how much capital (usually a percentage of your entire capital) you are willing to bet on a single deal. The position size is then determined by dividing this risk value by the difference between your entry price and stop-loss level. By preventing you from overcommitting to any one deal, this method helps you control risk and enables more consistent risk management throughout your trading portfolio.
Related Terms
- Option Adjusted Spread (OAS)
- Beta Risk
- Bear Spread
- Execution Risk
- Exchange-Traded Notes
- Dark Pools
- Firm Order
- Covered Straddle
- Chart Patterns
- Candlestick Chart
- After-Hours Trading
- Speculative Trading
- Average Daily Trading Volume (ADTV)
- Swing trading
- Sector-Specific Basket
- Regional Basket
- Listing standards
- Proxy voting
- Block Trades
- Undеrmargin
- Buying Powеr
- Whipsaw
- Index CFD
- Initial Margin
- Risk Management
- Slippage
- Take-Profit Order
- Open Position
- Trading Platform
- Debit Balance
- Scalping
- Stop-Loss Order
- Cum dividend
- Board Lot
- Closed Trades
- Resistance level
- CFTC
- Open Contract
- Passive Management
- Spot price
- Trade Execution
- Spot Commodities
- Cash commodity
- Volume of trading
- Open order
- Bid-ask spread
- Economic calendar
- Secondary Market
- Subordinated Debt
- Basket Trade
- Notional Value
- Speculation
- Quiet period
- Purchasing power
- Interest rates
- Plan participant
- Performance appraisal
- Anaume pattern
- Commodities trading
- Interest rate risk
- Equity Trading
- Adverse Excursion
- Booked Orders
- Bracket Order
- Bullion
- Trading Indicators
- Grey market
- Intraday trading
- Futures trading
- Broker
- Head-fake trade
- Demat account
- Price priority
- Day trader
- Threshold securities
- Online trading
- Quantitative trading
- Blockchain
- Insider trading
- Equity Volume
- Downtrend
- Derivatives
Most Popular Terms
Other Terms
- Variable Annuity
- Asset Swaps
- Anchoring Bias
- Alpha Capture
- Bond Convexity
- Compound Yield
- Brokerage Account
- Discretionary Accounts
- Industry Groups
- Growth Rate
- Green Bond Principles
- Gamma Scalping
- Funding Ratio
- Free-Float Methodology
- Foreign Direct Investment (FDI)
- Floating Dividend Rate
- Flight to Quality
- Real Return
- Protective Put
- Perpetual Bond
- Non-Diversifiable Risk
- Merger Arbitrage
- Liability-Driven Investment (LDI)
- Income Bonds
- Guaranteed Investment Contract (GIC)
- Flash Crash
- Equity Carve-Outs
- Cost of Equity
- Cost Basis
- Deferred Annuity
- Cash-on-Cash Return
- Earning Surprise
- Capital Adequacy Ratio (CAR)
- Bubble
- Asset Play
- Accrued Market Discount
- Ladder Strategy
- Junk Status
- Intrinsic Value of Stock
- Interest-Only Bonds (IO)
- Interest Coverage Ratio
- Inflation Hedge
- Industry Groups
- Incremental Yield
- Industrial Bonds
- Income Statement
- Holding Period Return
- Historical Volatility (HV)
- Hedge Effectiveness
- Flat Yield Curve
Know More about
Tools/Educational Resources
Markets Offered by POEMS
Read the Latest Market Journal
Lion-Phillip S-REIT ETF: Analysts Maintain Positive Outlook Despite Rate Headwinds
Brief Overview Phillip Securities Research maintains its ACCUMULATE recommendation on Lion-Phillip S-REIT ETF (SREITS) with a reduced target price of S$0.85, down from S$0.90. The ETF has undergone portfolio changes with Keppel DC REIT becoming the top holding, replacing CapitaLand Ascendas REIT, while Mapletree Logistics Trust remains the third-largest position. The fund continues to offer diversified exposure across retail, commercial, industrial and data-centre assets, balancing stable income with growth opportunities. Investment Positives The ETF's strongest advantage lies in its well-diversified portfolio structure across eight property sectors. Industrial assets form the largest allocation at 35.6%, followed by retail at 17.5%, providing investors with broad exposure across Singapore's REIT market while reducing concentration risk in any single sector. The diversified exposure to retail, commercial, industrial, and data-centre assets create a balanced investment proposition that combines stable rental income streams with structural growth opportunities. This diversificiation allows the ETF to benefit from different property cycles and tenant demand patterns across various sectors. Looking ahead, analysts expect organic rental growth to support the ETF's performance. In addition, easing domestic financing costs should provide tailwinds for the underlying REITs, contributing to a gradual recovery in distribution per unit (DPU) through FY27. Challenges The primary concern facing the ETF is uncertainty over the interest-rate outlook, which may limit near-term valuation upside. Interest rate movements typically have an inverse relationship with REIT valuations, and the current uncertain environment creates headwinds for immediate price appreciation. Outlook Despite near-term challenges from interest rate uncertainty, the analysts maintain a constructive medium-term outlook. The combination of organic rental growth and easing domestic financing costs is expected to support a gradual recovery in DPU throughFY27, providing a pathway for improved performance as interest rate concerns subside. Recommendation & Target Price Phillip Securities Research maintains its ACCUMULATE recommendation for Lion-Phillip S-REIT ETF. The analysts have lowered their target price to S$0.85 from the previous S$0.90, derived using a combination of historical dividend yield spread and price-to-book ratio methodologies, with equal weighting applied to both valuation approaches. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Semiconductor Sector Shows Strong Growth Acceleration Led by Custom ASIC Players
Brief Overview The semiconductor sector has demonstrated mixed performance over the past three months, with the Semiconductor ETF rising 2.4% but underperforming the S&P500's 4.1% gain. Equipment players faced headwinds due to elevated valuations, while memory companies declined amid HBM4 shipment uncertainties. However, enterprise and sovereign AI buildout is driving higher demand, with Coreweave and Nebius' combined remaining performance obligations reaching US$141 billion in June 2026. Investment Positives The semiconductor sector presents compelling growth opportunities across multiple segments. Custom ASIC companies are leading the acceleration, with Broadcom and Marvell guiding 3Q26e revenue to surge 89% year-on-year to a combined US$38 billion, surpassing the combined growth guidance of 83% from NVIDIA and AMD. Equipment manufacturers are experiencing robust demand, with their combined 3Q26e revenue guided to reach 52% year-on-year growth to US$31.4 billion, representing potentially the largest growth since 2021. This equipment demand is underpinned by TSMC's increased capital expenditure guidance of US$62 billion, marking a 15% increase, alongside memory players' higher equipment spending as new fabrication facilities ramp up production. The broadening customer base strengthens the sector's resilience. Coreweave and Nebius have expanded their client roster to include major enterprises such as Caterpillar, Grammarly, Databricks, Reflection, AI neolabs and quantitative trading firms. This diversification across AI neoclouds, enterprises and sovereign nations makes NVIDIA and AMD's growth more resilient should hyperscaler capital expenditure moderate. From a valuation perspective, large-cap SaaS companies are trading at roughly -1 standard deviation, with an EV/Sales multiple of 9.5x versus their 3-year average of 10.8x, suggesting attractive valuations despite strong performance. Enterprise and sovereign nations' AI buildout continues to drive substantial demand growth, with Coreweave and Nebius' combined remaining performance obligations increasing 72% from December 2025 to reach US$141 billion by June 2026. Challenges Valuation concerns persist in certain segments of the semiconductor sector. Equipment players AMAT and Lam Research have experienced significant pullbacks, declining 10.6% and 3.7% respectively, as they trade at elevated forward price-to-earnings ratios of 40x and 34x, compared with the sector average of 27x. Memory companies face headwinds from currency fluctuations and product transition uncertainties. SK Hynix declined 17% while Samsung fell 1.9%, laregly due to uncertainty surrounding HBM4 shipment timelines and the impact of a stronger Korean won on their financial performance. Outlook The outlook for the semiconductor sector remains positive, supported by accelerating growth across the custom ASIC, equipment and foundry segments. Revenue growth acceleration is expected in 3Q26e across these key areas, with custom ASIC companies leading the charge. The diversification of AI demand across multiple customer segments provides additional stability to the growth trajectory. Recommendation & Target Price Phillip Securities Research maintains an OVERWEIGHT recommendation on the semiconductor sector, reflecting confidence in the strong growth momentum of custom ASIC companies, equipment manufacturers and foundry operations. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Software Sector Stages Strong Recovery as AI Concerns Subside
Brief Overview The software industry has experienced a significant re-rating, with the iShares Software ETF (IGV) rebounding 17% in 3Q26 and now sitting just 7% below its September 2025 peak. SaaS LTM revenue growth accelerated to 17.5% YoY in 2Q26, marking the strongest growth in 15 quarters. Phillip Securities Research maintains an OVERWEIGHT stance on software, favouring SaaS infrastructure, data analytics, and cybersecurity as key AI beneficiaries. Investment Positives The software sector's recovery has been driven by easing concerns over AI disruption, with market leader Microsoft surging 30% following its 4Q26 results. Microsoft's performance was supported by Azure growth exceeding 40% YoY, no unexpected incremental capital expenditure announcements despite peers raising spending, and the introduction of usage-based billing. The rebound has also extended to data and AI platform companies, with Palantir gaining 61% and Snowflake rising 35% during the quarter. Salesforce also advanced following the launch of Claudeforce, its joint application with Anthropic, reinforcing the value of proprietary enterprise data despite increasingly capable AI models. Large-cap SaaS companies continue to outperform, benefiting from AI-tier upgrades, usage-based pricing, and seat expansion. These companies are enjoying higher sales growth of 18.2%, which is 0.7 percentage points higher year-on-year, as enterprises spend more on higher-priced AI tiers, increase adoption of usage-based pricing, and expand seat usage. Excluding Microsoft and Oracle, growth remained healthy at 16.3%. From a valuation perspective, large-cap SaaS companies are trading at roughly -1 standard deviation, with an EV/Sales multiple of 9.5x versus their 3-year average of 10.8x, suggesting attractive valuations despite strong performance. Challenges Cybersecurity valuations remain elevated, with companies trading at stretched multiples. This has led to concerns about sustainability of current price levels in this subsector, despite its strong year-to-date performance. Outlook The software sector appears to be emerging from what the research describes as the "SaaSpocalypse", with growth rates expected to persist in 3Q26e. The preferred investment areas include SaaS infrastructure, data analytics, and cybersecurity as key AI beneficiaries. Top picks are supported by strong AI adoption, expanding backlog conversion, and rising enterprise data demand. Recommendation & Target Price Phillip Securities Research maintains an OVERWEIGHT recommendation on the software sector. Preferred names include Microsoft, Oracle, Palantir, and Snowflake. However, the firm has downgraded Palo Alto Networks to NEUTRAL, as its valuation appears stretched, trading at 97x P/E versus its 5-year average of 54x. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Stoneweg Europe Stapled Trust Pursues Growth Through Management Internalisation
Brief Overview Stoneweg Europe Stapled Trust (SERT) is proposing to internalise its manager for €114 million at a 14% discount to independent valuation, creating a fully integrated European logistics and digital infrastructure platform with approximately €3.2 billion of assets under management. The transaction will be funded through issuing 40 million stapled securities to sponsor SWI Group at €2.00 each, representing a 33% premium to the last traded price of €1.50. Phillip Securities Research maintains a BUY recommendation with an unchanged target price of €1.89, highlighting the deal's immediate distribution per stapled security (DPS) accretion and growth potential. Investment Positives The internalisation presents compelling value creation opportunities for SERT. The acquisition pricing appears attractive at 7.1x P/EBIT based on the effective consideration of €94mn, significantly below the independent valuer's 10.1x multiple. This favourable valuation provides SERT with immediate financial benefits. The transaction is expected to deliver substantial DPS accretion of 5.9%, supported by approximately €11 million in third-party asset management fees and the elimination of external management fees. Even when excluding third-party asset management contracts, the deal remains 3.1% DPS accretive, demonstrating the inherent value of the internalisation structure. Strategically, the transaction brings SERT's pan-European logistics and light-industrial operating capabilities in-house while preserving access to growth opportunities. Strategic cooperation agreements maintain exclusive access to SWI Group's European logistics and light-industrial opportunitie, as well as preferred access to specialist data centre capabilities. This supports SERT's ambition to increase its logistics and light-industrial exposure towards 70% of its portfolio from the current 55.7%. Upon completion, SERT will manage approximately €3.2 billion of AUM and combine recurring property income with asset management earnings. The internalisation allows SERT to retain acquisition and asset management fees from future acquisitions, creating additional revenue streams and enhancing long-term profitability. Challenges The completion of this transaction faces several hurdles, remaining subject to regulatory and third-party consents, as well as securityholder approval at an extraordinary general meeting. These requirements introduce execution risk and potential delays to the anticipated benefits. Outlook The internalisation represents a significant strategic shift for SERT, positioning the trust as a fully integrated platform capable of capturing both property income and asset management earnings. The transaction also provides potential for further growth through data centre conversions and SERT's stake in AiOnX, while maintaining access to SWI Group's pipeline of opportunities. Recommendation & Target Price Phillip Securities Research maintains a BUY recommendation with an unchanged dividend discount model-derived target price of €1.89. The research house remains positive on the transaction given its immediate DPS accretion and potential to capture additional earnings from the integrated operating platform. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Brief Overview Phillip Securities Research has initiated coverage on Frasers Logistics & Commercial Trust (FLCT) with a BUY recommendation and a target price of S$1.01. The research highlights FLCT's resilient logistics and industrial portfolio, substantial acquisition pipeline from sponsor FPL, and attractive forward dividend yields of 6.8%. The trust is currently trading at a 21% discount to NAV. Investment Positives FLCT's logistics and industrial portfolio forms the cornerstone of its investment appeal, comprising 75.3% of portfolio value with an exceptional occupancy of 99.7%. The portfolio benefits from predominantly freehold and long leasehold assets, providing stable foundations for earnings generation. Rental growth prospects remain strong, with rental reversions reaching 11.9% in 3Q26 on an incoming-versus-outgoing basis and an impressive 23.8% on an average-versus-average basis. This reflects strong rental uplift amid tight market conditions and resilient domestic demand. The portfolio also benefits from built-in rental escalations, including annual increases averaging 3.2% in Australia and CPI-linked leases in Europe, supporting recurring rental income and organic DPU growth. The trust's acquisition capabilities represent a significant growth driver. FLCT has access to a sizeable ROFR pipeline exceeding S$5 billion from sponsor FPL, representing approximately 70% of its existing portfolio value. This provides substantial opportunities for inorganic DPU growth. The trust has demonstrated execution capability through its recent €294.9 million (S$441.5 million) acquisition of four logistics properties in Germany and the Netherlands, expected to be 1.7% DPU accretive. The commercial portfolio offers additional upside potential through backfilling opportunities. ATP is now 85.3% occupied following successful backfilling of approximately 83% of space previously vacated by Google, whilst UK business parks achieved occupancy rates between 81.5% and 87.6%. Further backfilling of remaining vacancies could provide meaningful earnings enhancement. Challenges The research notes that FLCT's commercial portfolio currently operates at an occupancy rate of 88.4%, indicating that vacancy challenges remain and need to be addressed to optimise returns. Outlook The analysts forecast FY26e and FY27e DPU of 5.90 cents and 5.93 cents respectively, translating to attractive forward dividend yields of 6.8%. Potential re-rating catalysts include DPU-accretive acquisitions, divestments of mature non-core assets for capital recycling, and continued commercial portfolio backfilling. Recommendation & Target Price Phillip Securities Research has initiated coverage with a BUY recommendation and DDM-derived target price of S$1.01. The trust trades at a 21% discount to NAV, representing a level that is 1.4 standard deviations below its historical mean P/NAV. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
JEP Holdings Ltd Positioned for Multi-Year Growth in Semiconductors and Aerospace
Brief Overview Phillip Securities Research has initiated coverage of JEP Holdings Ltd with a positive outlook, highlighting the company's strategic pivot from traditional aerospace manufacturing to specialised semiconductor components. The analyst expects the company to benefit from a new partnership with a major semiconductor customer, continued aerospace recovery, and organic growth through its parent company, UMS Integration. Net profit is projected to almost quadruple from FY25 to FY27e. Investment Positives The most significant growth driver identified is JEP's partnership with a major front-end semiconductor customer to supply specialised plastic components. These components are believed to be used in wet etch, deposition and plating processes of advanced semiconductor packaging for next-generation AI chips. JEP has proactively invested in new capacity ahead of what the analyst expects to be a multi-year ramp, with the company increasing capex spending by more than 2x year-on-year to S$20.6 million in FY25 to expand capabilities in Singapore. Mass production of these specialised plastic components is expected to drive equipment revenue in FY27e up by more than 100% year-on-year to approximately S$50 million. The aerospace segment presents another compelling opportunity, with stronger demand emerging from improved aircraft deliveries. Bottlenecks in aircraft deliveries are easing, and widebody deliveries are expected to increase by 13% CAGR over the next three years. Boeing has increased its 787 Dreamliner production target from 8 to 10 jets monthly by 2026 and expects the first delivery of its 777X widebody jet programme by 2027e. JEP's aerospace revenue rose 37.5% year-on-year to S$15.8 million in 1H26, driven by stronger widebody aircraft deliveries. The company also benefits from its relationship with its parent company UMS Integration, with approximately 30% of JEP's semiconductor metal part orders coming from UMS. The analyst notes that JEP's aerospace-grade machining capabilities can be applied to manufacturing semiconductor parts. In 1H26, semiconductor revenue surged 23% year-on-year to S$8.4 million, driven by AI-led semiconductor capex upcycle. Challenges The report does not explicitly identify significant investment challenges or risks facing JEP Holdings. Outlook The analyst maintains an optimistic outlook, expecting JEP to ride on the organic growth of its parent company UMS Integration. As both UMS and JEP's key semiconductor front-end equipment customers have raised expectations for 2026 WFE spend to approximately US$150 billion (previously US$135-140 billion), this is expected to drive demand for JEP's semiconductor revenue. Recommendation & Target Price Phillip Securities Research initiates coverage with a BUY recommendation and target price of S$0.83. The target price is based on 28x FY27e P/E, representing a 7% discount to peers' average forward P/E of 30x. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Snowflake Inc – Growth from Rising Coding and AI Agent Activities
Brief Overview Phillip Securities Research highlights that rising enterprise data volumes and AI adoption are accelerating cloud-native platform adoption, with the global data lake market projected to reach US$45.8 billion by 2030. AI products contributed roughly half of 2Q27 growth acceleration, with CoCo and CoWork surpassing 9,100 and 5,800 adopted accounts respectively, helping drive 37% YoY product revenue growth. The firm initiates coverage with a BUY recommendation and DCF-based target price of US$423. Investment Positives The investment case for Snowflake is anchored on several compelling growth drivers. Rising enterprise data volumes and AI adoption are accelerating the shift from on-premises infrastructure to cloud-native data platforms. Enterprises increasingly require scalable, cost-efficient storage and compute capabilities to manage growing datasets and support AI workloads, driving demand for modern data architectures. IBM estimates the global data lake market will reach US$45.8 billion by 2030, representing a 23.9% CAGR from 2024, supporting a sizeable long-term growth opportunity for Snowflake. AI products are proving to be a significant catalyst, contributing roughly half of growth acceleration in 2Q27. This was driven by the rising adoption of CoCo and CoWork, with over 9,100 and 5,800 adopted accounts respectively. Expanding AI coding, agent, and application development workloads helped drive 37% YoY product revenue growth to US$1.5 billion in 2Q27 and contributed to Snowflake's strongest revenue growth in three years. The consumption-based model provides significant leverage to AI adoption. With 95% of revenue being consumption-based, usage is directly linked to revenue. Growing analytics and AI workloads drive higher compute usage, with AI being far more compute-intensive than traditional analytics. Growth is driven by both new customers and higher consumption from existing customers. Customers purchase credits upfront and consume them as workloads run, whilst higher-value products drive greater usage, credit consumption, and spending. Challenges The report does not explicitly outline specific investment challenges or risks facing Snowflake. Outlook The analyst forecasts strong growth momentum, projecting product revenue to grow 36% YoY to US$6.08 billion in FY27e, with adjusted EPS rising 63% YoY and an adjusted FCF margin of 23.8%. The consumption-based revenue model directly links AI-driven compute usage to revenue growth as customers consume more credits and increase spending on higher-value workloads. Recommendation & Target Price Phillip Securities Research initiates coverage with a BUY recommendation and a DCF-based target price of US$423, based on a 5.7% WACC and 5.1% terminal growth rate. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
City Developments Limited Charts Clear Growth Path with Strategic Overhaul
Brief Overview City Developments Limited has unveiled its 'GET+' three-year roadmap for FY27-FY29, positioning Singapore as its core market while executing a major exit from Australia across all sectors except hospitality assets. The strategic review targets S$5 billion of growth investments and S$6 billion of divestments to unlock value and achieve deleveraging goals. The company aims to establish a dedicated fund management platform to double assets under management to S$10 billion across listed and private platforms. Investment Positives The strategic review delivers several compelling growth drivers that strengthen CDL's investment proposition. The roadmap provides greater clarity on capital allocation priorities and establishes a credible path to deleveraging, addressing a key concern for investors. The S$6 billion divestment programme represents a significant value unlock opportunity, with over S$1 billion of profit after tax and minority interests expected from divestment gains, equivalent to approximately S$1.12 per share. The monetisation strategy is well-diversified, comprising S$2.7 billion in commercial assets, S$1.8 billion in hotels, and S$1 billion in residential properties across the UK and Australia. CDL's fund management expansion offers particularly attractive prospects for sustainable growth. The dedicated fund management entity aims to double assets under management from S$5 billion to S$10 billion by FY29, encompassing both listed REIT platforms and an expanded private capital platform through funds, partnerships and joint ventures. This initiative supports a more capital-light growth model whilst building a recurring fee income stream and improving capital efficiency, potentially supporting higher return on equity over time. The company's development pipeline remains robust, with over S$6 billion of projected property development cash inflows from existing projects providing additional financial strength. The growth investment strategy is geographically focused, with 60% allocated to Singapore, 30% to China and Japan, and 10% to other markets across residential, commercial, hospitality and living sectors. Outlook The strategic review establishes four key financial targets that define CDL's trajectory through FY29. The company aims to achieve a dividend payout of at least 35% of reported profit after tax and minority interests annually, whilst reducing net gearing from 75% as at 1H26 to 55% by FY29. The divestment programme targeting over S$1 billion of profit realisation, combined with the doubling of assets under management, positions the company for enhanced capital efficiency and sustainable growth. Recommendation & Target Price Phillip Securities Research maintains a BUY recommendation with an unchanged RNAV target price of S$11.32, representing a 25% discount to the RNAV of S$15.09. No changes have been made to existing forecasts following the strategic review announcement. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.