Over-the-counter stocks
Table of Contents
Over-the-counter stocks
Unlisted stocks are another name for over-the-counter (OTC) stocks. In contrast to stock exchanges such as the New York Stock Exchange or Nasdaq, they are often supplied by small businesses and exchanged by market makers.
Bonds, stocks, and other financial instruments can be exchanged directly between two parties through the OTC (over-the-counter) market rather than on a public stock exchange like the NYSE or Nasdaq. A benefit of investing in OTC securities is that you can buy a successful stock early.
What are OTC stocks?
Over-the-counter (OTC) stocks are not traded on a formal exchange like the New York Stock Exchange (NYSE). Instead, they are traded through a network of broker-dealers who directly negotiate with one another over the phone or electronically.
Whether or not investing in OTC markets is right for you will come down to your investment goals and risk tolerance. If you are comfortable with a bit more risk and are looking for more flexibility in your investment strategies, OTC markets may be worth considering. However, traditional exchanges may be better if you prefer a more stable and regulated environment.
Understanding OTC stocks
OTC stocks often trade for less per share than corporations whose shares are listed on an exchange. Many OTC companies, sometimes referred to as penny stocks or micro-cap stocks, trade for less than 5 USD per share. The low cost may make them appealing to individual investors. These cheap shares, however, can be dangerous and extremely speculative.
Several electronic platforms are used for OTC transactions. The US’ Financial Industry Regulatory Authority (FINRA) ran one of the most well-known ones, the OTC Bulletin Board (OTCBB), until selling it to the investment bank Rodman & Renshaw.
Types of OTC securities
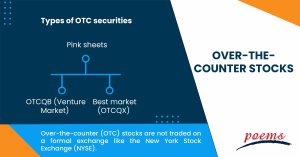
There are three major types of over-the-counter (OTC) stocks in the United States:
- Pink sheets
The Pink Sheets are stocks not listed on a major exchange, such as the Nasdaq or the New York Stock Exchange.
- OTCQB (Venture Market)
The intermediate tier, the OTCQB, has a high proportion of emerging businesses and is sometimes referred to as the “venture market”. OTCQB companies are subject to monitoring and must disclose their financial information.
- Best market (OTCQX)
This is the pickiest. Only 4% of the OTC equities listed on this exchange are traded here. It typically consists of international firms that list on significant overseas exchanges and certain US companies that want to someday list on the NYSE or the Nasdaq and have the highest reporting criteria and toughest scrutiny.
How to buy OTC stocks?
You can sell and purchase OTC stocks using most top online brokers because they trade similarly to most other equities. You must be aware of the corporation’s ticker symbol and also have sufficient funds in your brokerage account to purchase the necessary number of OTC shares.
OTCs cannot be bought directly through the OTC Markets Group or the Over-the-Counter Bulletin Board (OTCBB). Instead of using individual investors, market makers handle all transactions.
It’s critical to remember that all investments have risk and that investors should carefully evaluate their investment objectives before investing.
When finding a reputable broker, it is important to look for a member of FINRA. Finding a broker with experience trading OTC stocks is also important.
How are OTC stocks different?
The volume of publicly available corporate information is the primary distinction between an OTC and a listed stock. It can be challenging to discover information on OTC companies, which leaves investors more open to investing in fraud schemes and reduces the likelihood that reported market values are based on accurate and comprehensive data on the company.
A company might choose to list its stock on an OTC exchange instead of a formal exchange because it may not meet the listing requirements of a formal exchange. For example, the NYSE requires a company with a minimum market capitalisation of 100 million USD and that it has been profitable for at least four of the past five years.
Another reason a company might choose to list on an OTC exchange is that it may be a start-up or small company that cannot afford the high listing fees of a formal exchange.
Generally speaking, OTC stocks are riskier than stocks listed on a formal exchange. This is because there is less information available about OTC stocks and because they are not subject to the same level of regulation.
Frequently Asked Questions
You can purchase and sell OTC stocks if you use a full-service brokerage in the real world. For the stock you want to purchase or sell, the broker must place an order with the market maker. The OTCBB allows for continuous monitoring of bid and ask prices.
OTC stocks have lower volatility than their exchange-traded counterparts, lower trading volume, wider gaps between the bid and ask prices, and less information available to the general public. As a result, they are risky investments that are frequently speculative.
Pros of OTC markets:
- On the plus side, OTC markets tend to be much less regulated than traditional exchanges.
- Additionally, OTC markets often have lower costs associated with trading since there are no listing fees or other exchange-related charges.
Cons of OTC markets:
- One is that OTC markets can be more volatile and less liquid than traditional exchanges, making buying and selling securities more difficult.
- Additionally, OTC markets can be more susceptible to fraud and manipulation since regulatory bodies have less oversight.
For instance, you may frequently locate foreign equities on the OTC markets, including those of several significant corporations. One suitable illustration is Nestle (OTC: NSRGY). The food and beverage corporation, which has its headquarters in Switzerland, principally trades on the SIX Swiss Exchange.
However, it also offers its shares on the Euronext and OTC markets to make it easier for investors to purchase shares without convenient access to the Swiss stock exchange.
A few things to remember when selling OTC stocks.
- First, it’s important to know the difference between OTC and exchange-traded stocks. OTC stocks are not traded on exchanges like the New York Stock Exchange (NYSE) or the Nasdaq.
- Instead, they are traded through networks of brokers and dealers. This means that the prices of OTC stocks can be more volatile and less transparent than exchange-traded stocks.
- Second, OTC stocks are often less liquid than exchange-traded stocks. This means that it may be more difficult to find buyers for OTC stocks and that the prices of OTC stocks can be more volatile.
- Finally, OTC stocks are often penny stocks, which trade for less than 5 USD per share. Penny stocks are generally riskier than exchange-traded ones and are often subject to manipulation by insiders.
For all these reasons, it’s important to be careful when selling OTC stocks. Make sure you understand the risks involved, and consult with a financial advisor if you have any questions.
Related Terms
- Merger Arbitrage
- Intrinsic Value of Stock
- Callable Preferred Stock
- Growth Stocks
- Market maker
- Authorized Stock
- Dividend Discount Model
- Stock Shifts
- Seasoned Equity Offering
- Price to Book
- Stock Price
- Consumer Stock
- Undervalued Stocks
- Tracking Stock
- Income stocks
- Merger Arbitrage
- Intrinsic Value of Stock
- Callable Preferred Stock
- Growth Stocks
- Market maker
- Authorized Stock
- Dividend Discount Model
- Stock Shifts
- Seasoned Equity Offering
- Price to Book
- Stock Price
- Consumer Stock
- Undervalued Stocks
- Tracking Stock
- Income stocks
- Hang Seng Index
- Rally
- Ticker Symbol
- Defensive stock
- Earnings Guidance
- Wire house broker
- Stock Connect
- Options expiry
- Payment Date
- Treasury Stock Method
- Reverse stock splits
- Ticker
- Restricted strict unit
- Gordon growth model
- Stock quotes
- Shadow Stock
- Margin stock
- Dedicated Capital
- Whisper stock
- Voting Stock
- Deal Stock
- Microcap stock
- Capital Surplus
- Multi-bagger Stocks
- Shopped stock
- Secondary stocks
- Screen stocks
- Quarter stock
- Orphan stock
- One-decision stock
- Repurchase of stock
- Stock market crash
- Half stock
- Stock options
- Stock split
- Foreign exchange markets
- Stock Market
- FAANG stocks
- Unborrowable stock
- Joint-stock company
- Watered stock
- Zero-dividend preferred stock
- Bid price
- Authorised shares
- Auction markets
- Market capitalisation
- Arbitrage
- Market capitalisation rate
- Garbatrage
- Autoregressive
- Stockholder
- Penny stock
- Noncyclical Stocks
- Hybrid Stocks
- Large Cap Stocks
- Mid Cap Stocks
- Common Stock
- Preferred Stock
- Small Cap Stocks
- Earnings Per Share (EPS)
- Diluted Earnings Per Share
- Dividend Yield
- Cyclical Stock
- Blue Chip Stocks
- Averaging Down
Most Popular Terms
Other Terms
- Variable Annuity
- Asset Swaps
- Anchoring Bias
- Alpha Capture
- Bond Convexity
- Compound Yield
- Brokerage Account
- Discretionary Accounts
- Industry Groups
- Growth Rate
- Green Bond Principles
- Gamma Scalping
- Funding Ratio
- Free-Float Methodology
- Foreign Direct Investment (FDI)
- Floating Dividend Rate
- Flight to Quality
- Real Return
- Protective Put
- Perpetual Bond
- Option Adjusted Spread (OAS)
- Non-Diversifiable Risk
- Liability-Driven Investment (LDI)
- Income Bonds
- Guaranteed Investment Contract (GIC)
- Flash Crash
- Equity Carve-Outs
- Cost of Equity
- Cost Basis
- Deferred Annuity
- Cash-on-Cash Return
- Earning Surprise
- Capital Adequacy Ratio (CAR)
- Bubble
- Beta Risk
- Bear Spread
- Asset Play
- Accrued Market Discount
- Ladder Strategy
- Junk Status
- Interest-Only Bonds (IO)
- Interest Coverage Ratio
- Inflation Hedge
- Industry Groups
- Incremental Yield
- Industrial Bonds
- Income Statement
- Holding Period Return
- Historical Volatility (HV)
- Hedge Effectiveness
Know More about
Tools/Educational Resources
Markets Offered by POEMS
Read the Latest Market Journal
Phillip Securities Research Morning Call: Market Updates and Strategic Outlook – 5 Oct 2026
The latest Phillip Securities Research Morning Call provided comprehensive insights into market developments, featuring updates on Micron's quarterly results, CDL's strategic review, technical analysis of major indices, and Singapore's economic indicators. The session highlighted both opportunities and challenges across various sectors and geographies. Micron Shows Promising Signs with Strategic Customer Agreements Micron Technology delivered fourth-quarter results that met expectations, with revenue and earnings driven primarily by rising average selling prices (ASPs) for both DRAM and NAND memory products amid ongoing shortage conditions. The most significant development was Micron's announcement of 10 new Strategic Customer Agreements (SCAs), bringing the total to 26 agreements expected to exceed 35% of revenue through 2030. These SCAs represent a marked improvement over previous long-term contracts, featuring stricter terms including "take or pay" contracted volumes requiring 20% deposits and price floors to mitigate future downcycles. This structure should provide greater revenue stability and earnings predictability for the memory giant. However, Micron also announced higher capital expenditure guidance for the first half of fiscal 2025, representing more than 60% of previous guidance. Management justified this increase as necessary to meet customer demand through facility expansions in the US, Singapore, and Taiwan. Looking ahead, Micron anticipates substantial share repurchases starting 9 December, as the two-year CHIPS Act restriction period expires. The company plans to return 100% of excess cash through buybacks, potentially totaling US$70 billion based on current projections, which could boost earnings per share by approximately 6%. CDL's Strategic Review Faces Market Scepticism City Developments Limited (CDL) unveiled its "GET Plus" strategy, a three-year plan focusing on four core sectors: residential, commercial, hospitality, and living. The strategy involves US$5 billion in growth investments and US$6 billion in divestments for capital recycling and deleveraging. Key objectives include maintaining dividend payouts above 35% of reported earnings, reducing leverage to 55% by FY2029 from current levels of 75%, and doubling assets under management from US$5 billion to US$10 billion. The company expects to unlock over US$1 billion in divestment gains from the planned asset sales. Despite these ambitious plans, CDL's share price declined 15% following the announcement. Market scepticism stems from the lack of detailed financial outcomes, absence of specific ROE targets, and limited visibility on the financial benefits of the strategy. Unlike comparable strategic reviews by peers like Hong Kong Land, CDL's plan was perceived as less concrete and execution-dependent. The geographic focus remains on Singapore as the core market, with plans to gradually exit Australia except for hospitality assets. Of CDL's 54 owned hotels valued at US$8.6 billion, management categorised 60% as core assets to retain, 20% for enhancement through asset improvement or redevelopment, and 20% (US$1.8 billion) for divestment. Strong Singapore Economic Data Signals Recovery Singapore's economic indicators showed remarkable strength, with the PMI reaching its highest level in almost eight years and accelerating from the previous month. The banking sector demonstrated exceptional loan growth of 13.5%, representing a record acceleration and doubling the 6% growth from a year ago. This robust loan growth, driven primarily by data centers, technology, energy, renewables, and acquisition financing, provides banks with both volume increases and pricing power as SORA rates turn positive year-over-year. Manufacturing remains the fastest-growing loan segment, while housing and consumer loans maintain stable mid-single-digit growth rates. The strong economic momentum in Singapore contrasts with challenges elsewhere, as semiconductor exports from Korea continued robust growth at 26.3% in September, indicating sustained demand in the technology sector. Technical Analysis Points to Cautious Optimism The S&P 500 showed resilience despite a slight 0.2% decline last week, holding key support at 5,655 around the gap-fill level and 20-day moving average. The index maintained its breakout above a wedge consolidation pattern, with Friday's gap higher suggesting continued underlying strength. Historical analysis of weak market breadth conditions provides encouragement. When less than 25% of S&P 500 constituents trade above their 50-day moving averages – a condition that occurred on 20 September – markets have historically performed well afterward, averaging 1.8% gains one week later and nearly 16% a year later. September proved challenging across most asset classes, with only Bitcoin ETFs posting gains (+5.4%) while gold ETFs declined 6.7%. October expectations remain muted, with most assets likely to consolidate sideways, though gold, Singapore equities, and the Hang Seng Index may extend their weakness. EQDP Program Shows Structural Impact on Small-Mid Caps The Equity Development Partnership Program (EQDP) continues demonstrating its structural catalyst effect on Singapore's small and mid-cap stocks. Since the program's announcement in February, dedicated Singapore equity funds have grown five-fold from US$1 billion to US$5 billion by August, with OCBC's fund expanding most dramatically from US$200 million to US$2 billion. The program has also increased institutional participation, with more small-mid cap stocks achieving 5% institutional stakes. While recent performance has been mixed, the historical pattern shows strong outperformance typically occurs 6-12 months after fund allocation rather than immediately following announcements. Sector Outlook: Semiconductors and Oil & Gas Favored For attractive EQDP allocation targets, analysts favor the semiconductor sector, noting the upcycle only began in early 2024 when TSMC raised capital expenditure. Singapore semiconductor companies are just beginning to show earnings improvement from this cycle, suggesting continued momentum ahead. The oil and gas sector also presents opportunities due to expected capital expenditure increases driven by high oil prices and energy security concerns. However, the construction sector faces headwinds from elevated diesel prices related to Middle East conflicts, though private sector demand shows signs of strengthening with contract awards up 25% year-to-date through July. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Micron Technology Strengthens Position with Strategic Customer Agreements
Brief Overview Micron Technology reported strong fourth-quarter 2026 results with revenue and adjusted PATMI within expectations, driven by a dramatic surge in memory pricing. The company secured 10 new strategic customer agreements during the quarter and provided an optimistic outlook for memory market conditions. Phillip Securities Research maintains a BUY recommendation with a raised target price. Investment Positives Micron's strategic positioning has strengthened significantly through new customer agreements. The company signed 26 Strategic Customer Agreements (SCAs) to date, up from 16 in the third quarter of 2026, which management guided to represent over 35% of revenue through 2030. These agreements feature much stricter terms than previous long-term contracts, including cash deposits and take-or-pay contracted volumes with price floors. Two SCAs were extended by a year to 2031, demonstrating customer commitment to long-term supply security. The financial impact of these agreements is substantial. Remaining performance obligations rose to approximately US$150 billion from US$100 billion in the third quarter, representing 13% higher than FY26 revenue. Financial commitments increased 45% to US$32 billion from US$22 billion, with the majority consisting of cash deposits. Memory pricing has surged dramatically, driving exceptional profitability. DRAM and NAND average selling prices spiked by an estimated 232% and 383% year-on-year respectively, propelling fourth-quarter 2026 net profit up more than 10-fold to US$38.4 billion. Gross and net margins reached record levels of 87% and 71% respectively, compared to 85% and 70% in the previous quarter. Supply constraints are expected to persist, supporting pricing strength. Cleanroom space across the industry remains constrained, as new fabrication facility expansions typically require 2-4 years to complete. Management expects memory and storage conditions to be "much tighter" in 2027 and 2028 than the current year, with hyperscalers and high-end processor chip companies prioritising memory supply security through 2031 with approximately 20% cash deposits. Challenges The report does not explicitly identify significant investment negatives or challenges facing Micron Technology. Outlook Micron anticipates a worsening memory and storage shortage from 2027-2028, which should support continued strong pricing and profitability. The company plans to return all excess cash to shareholders, primarily through buybacks, starting from 9 December 2026 when CHIPS Act restrictions end. The base case projection suggests returning approximately US$70 billion in FY27, equivalent to roughly US$1,100 per share, potentially boosting earnings per share by about 6%. Recommendation & Target Price Phillip Securities Research maintains a BUY recommendation with a raised target price of US$1,950, up from the previous US$1,870. The analysts increased FY27 revenue and adjusted PATMI forecasts by 11% and 22% respectively due to expected rises in DRAM and NAND prices, whilst lowering FY27 price-to-earnings assumptions to 12x from 14x. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
PhillipCapital Strategy & Stock Picks 4Q2026: Key Sectors and Equity Market Outlook
Brief Overview Singapore equities posted their fifth consecutive and strongest quarterly gain, rising 9.8% in 3Q26 and reaching a fresh record on 4 September. A 22% year-to-date advance ranks Singapore as Asia's fourth-best performer. Banks led the outperformance on above-consensus 2Q26 results driven by a jump in wealth management fees, while shipbuilders rallied on an order book recovery as US-to-China container freight rates surged 36%. Cost pressures and demand headwinds weighed on consumer and food-related counters, and a spike in bond yields triggered a de-rating across S-REITs. Investment Positives The Equity Development Programme (EQDP) has served as a structural catalyst for Singapore's small-mid cap stocks. Now in its 3rd phase — with S$5.4 billion of the S$6.5 billion allocation announced cumulatively — EQDP has driven a rally in small-mid caps since its February 2025 announcement. Institutional participation has become more significant, with higher-conviction ownership in small-mid cap names, and Singapore-dedicated equity fund assets under management soared almost five-fold over the past eight months. Rising global bond yields are not expected to derail growth. Higher yields mirror improving economic conditions, and aggressive AI-driven capital expenditure is accelerating corporate demand for capital, marking a transition from a savings glut to a capital-starved world. Banks remain a favoured sector, with rising interest rates providing pricing power alongside loan volume growth. Semiconductors are viewed especially positively — the earnings upcycle has only just begun this year, making the sector an attractive EQDP target. Oil and gas enjoy a revival due to energy security concerns, firmer oil prices stimulating a capex cycle, and Offshore Support Vessel operators benefiting from an ageing fleet and tight yard capacity. A 60% year-to-date rally in coal prices alongside a 50% output expansion provides strong earnings leverage for Geo Energy. In construction, building materials and dormitories are preferred segments, with order momentum expected to peak post Terminal 5 awards. Singtel was added to the Absolute 10 portfolio, offering structural earnings and monetisation drivers through data centres and GPU-as-a-Service, with mobile price repair underway across multiple Asian markets. Challenges Uncertainty over bond yields and inflation risk from the Middle East conflict keeps REITs under pressure. The Fed raised rates by 25 basis points to 3.75–4.00%, with further tightening likely, and rate expectations swung up 112 basis points from December 2025 to September 2026. Rising government bond yields have made Singapore equities less attractive, with the earnings yield spread over two-year bond yields at multi-year and one standard deviation lows, potentially capping overall market multiples. Property stocks have de-rated due to interest rate worries, with high rates in Australia and the UK dampening valuations and asset monetisation efforts. Hospitals and consumer sectors face headwinds — insurance payers are pressuring healthcare providers on pricing, while consumer spending continues to reel from rising inflation. REITs fell 10% this year, with 17 REITs or trusts hitting new 52-week lows in a single week. Outlook Singapore equities trade at a premium 17x PE, above the historical average of 15x, but this is justified by growing earnings momentum across multiple sectors. The key risk is whether elevated bond yields begin to present headwinds. The Absolute 10 model portfolio rose 5.5% in 3Q26, underperforming the broader market's 9.8% gain, with drags from profit-taking in Frencken and poor results from Sembcorp Industries. Recommendation & Target Price In the Absolute 10 model portfolio for 4Q26, Phillip Securities Research removed Stoneweg Europe Stapled Trust and added Singtel. The portfolio maintains overweight positions in banks, semiconductors, and oil and gas, while remaining underweight REITs, hospitals, and consumer sectors. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
AvePoint Inc.: AI Revolution Drives Demand for Independent Data Governance Solutions
Brief Overview AvePoint Inc., a US-headquartered SaaS company, has achieved a historic milestone by completing a secondary listing on the Singapore Exchange in September 2025, becoming the first of its kind to dual list in Singapore. The company is well-positioned to benefit from the surge in global AI spending, which is forecast to grow 49.5% year-on-year to US$2.7 trillion in 2026. With 73% of organisations already operating hybrid-cloud environments, the increasing complexity of AI-related data, security and costs is driving demand for independent governance solutions. Investment Positives The analyst identifies several compelling investment merits for AvePoint. AI adoption is creating dual opportunities in governance and cost optimisation. As AI-driven errors can propagate and cause significantly greater damage than human errors within short timeframes, enterprises are increasingly requiring fast recovery capabilities to minimise operational disruption. Simultaneously, the rapid escalation in AI spending is making cost optimisation a critical priority for companies scaling their AI adoption. AvePoint addresses these challenges by helping enterprises optimise costs across three key areas: identifying underutilised licences to right-size software spending, clearing redundant data to reduce cloud storage and training costs, and implementing agent cost tracking to rationalise underutilised agents and reduce overall AI expenditure. The company's multi-platform approach creates a structurally competitive advantage. As enterprises increasingly adopt fragmented combinations of Microsoft, Google, Salesforce, AWS and other platforms to access best-of-breed capabilities whilst comparing costs and avoiding excessive vendor dependence, the need for independent oversight grows. Individual vendors can only provide analytics within their own ecosystems and lack visibility across broader IT environments. This positions AvePoint favourably as an independent player capable of consolidating data, usage, governance, and cost insights across multiple platforms into a single control layer. AvePoint has demonstrated sustained strong financial performance with structurally improved profitability. Annual Recurring Revenue increased from US$215 million in FY22 to US$417 million in FY25, representing a 25% compound annual growth rate. Growth remained robust at 27% year-on-year in 2Q26. Non-GAAP operating margin expanded significantly from -1.2% in FY22 to 18.9% in FY25. Challenges The analyst notes that increased investments to capture AI-related opportunities are expected to temporarily moderate margins in FY26. However, non-GAAP operating income is still guided to grow 10% year-on-year despite these investment pressures. Outlook The analyst expects continued strong performance with revenue growth of 23% in FY26e and 20% in FY27e, reflecting the company's strong positioning in the evolving AI landscape. Recommendation & Target Price Phillip Securities Research initiates coverage of AvePoint Inc. with an ACCUMULATE rating and a target price of S$20.00. The valuation is based on a discounted cash flow analysis utilising a 7.9% weighted average cost of capital and a 5.0% growth rate. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
ETF Monthly Review: Mixed September Performance with Muted October Outlook Expected
Brief Overview September proved challenging for most ETFs, with the gold-tracking ETF (GLDM) suffering the steepest decline of 6.7%, whilst the Bitcoin ETF (BITO) stood as the sole gainer with a 5.4% rise. Current market conditions show most major asset classes in range consolidation, though US Treasury Bonds, Gold, and the Hang Seng Index remain in downtrends. October is anticipated to bring sideways consolidation for some assets whilst others may extend their weakness. Investment Positives Limited bright spots emerged from September's performance, with Bitcoin demonstrating notable resilience. The ProShares Bitcoin Strategy ETF gained 5.4% in September, marking its third consecutive month of positive performance. This sustained momentum reflects continued strength in the cryptocurrency space despite broader market challenges. The S&P 500 showed relative stability, with the Vanguard S&P 500 ETF experiencing only a modest 0.3% decline during September. This minimal pullback suggests underlying market resilience in US equities, with the index maintaining its position within a range consolidation pattern. Several ETFs are positioned for sideways consolidation in October, indicating potential stability ahead. The S&P 500 ETF is expected to find support in the US$697.50 to US$704.30 area, whilst the oil-focused XOP ETF may trade within a defined range between US$172 and US$185. Challenges Gold faced significant headwinds in September, with the SPDR Gold MiniShares Trust tumbling 6.7% to become the month's worst performer. The precious metal has entered a clear downtrend, raising concerns about further weakness ahead. US Treasury Bonds encountered notable pressure, with the iShares 7-10 Year Treasury Bond ETF declining 3.3% in September. This asset class has shifted into a downtrend pattern, reflecting challenging conditions in the fixed income market. Asian markets demonstrated vulnerability, with the Hang Seng China Enterprises Index ETF pulling back 3% for the second consecutive month, maintaining its downtrend status. Singapore Equities also showed weakness, with the relevant ETF snapping a five-month winning streak by declining 0.7%. Oil markets faced headwinds with the SPDR S&P Oil & Gas Exploration & Production ETF pulling back 4.7% during September, though it remains within a range consolidation pattern. Outlook October is expected to deliver muted performance across most asset classes. Four major ETFs - those tracking the S&P 500, US Treasury Bonds, Oil, and Bitcoin - are anticipated to consolidate sideways during the month. However, three asset classes face potential further weakness. Gold may extend its decline and potentially retest the US$78.33 swing low from late June, representing a 4.5% downside risk. Singapore Equities could fall to the US$5.59 support level if they break below US$5.72, indicating a possible 2.2% decline. The Hang Seng Index may retest support at HK$80.70, suggesting a potential 1.6% downside. Recommendation & Target Price The report provides specific technical levels and percentage projections for various ETFs but does not include an overall investment recommendation or target prices. The analysis focuses on directional expectations, with some assets expected to consolidate whilst others may extend their current weakness into October. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Adobe Inc – No inflection point in sight
Brief Overview Adobe delivered third quarter fiscal 2026 results that met expectations, with revenue and adjusted profit after tax and minority interests achieving 74% and 78% of full-year forecasts respectively. Growth was primarily driven by the Adobe Creative Cloud Pro deal, whilst Creative freemium monthly active users grew over 70% year-on-year, surpassing 100 million. Management raised fiscal 2026 guidance only marginally, and leadership continuity was assured with Chakravarthy set to succeed Shantanu Narayen as CEO in December 2026. Investment Positives Adobe demonstrates strengthening activity across its Creative products portfolio. Creative & Marketing Professionals revenue grew 13% year-on-year to US$4.65 billion, supported by continued momentum in Creative Cloud Teams and Enterprise offerings. The freemium strategy is gaining significant traction, with Creative freemium monthly active users surpassing 100 million and growing over 70% year-on-year, driven by strong adoption of Firefly, Express, Premiere, Photoshop and Lightroom. Artificial intelligence engagement continues to deepen across Adobe's platform, with credit consumption accelerating quarter-on-quarter. Firefly annual recurring revenue across the Firefly App and credit packs grew 40% quarter-on-quarter, reflecting rising monetisation of Adobe's AI offerings and the company's AI-first annual recurring revenue exceeding US$650 million. The document workflow segment shows ongoing expansion, with Business Professionals & Consumers revenue increasing 16% year-on-year to US$1.91 billion. This growth was supported by the strong adoption of Acrobat and Express products. Combined monthly active users exceeded 900 million, growing over 25% year-on-year, whilst Acrobat AI Assistant monthly active users doubled quarter-on-quarter. Adobe continues expanding Acrobat into an AI-powered productivity platform, incorporating new capabilities such as document summarisation, interactive reports, presentation slides and knowledge extraction across large document collections, driving both engagement and enterprise adoption. Challenges Despite the strong AI performance, Adobe's fiscal 2026 ending annual recurring revenue growth guidance was maintained at 10.2% compared to 11.5% in fiscal 2025, reflecting a continued emphasis on user acquisition and engagement over monetisation. This suggests the company has not yet reached an inflection point where its AI investments translate into accelerated revenue growth. Outlook The stock's recovery has been supported by evidence that AI complements Adobe's business model, strong AI engagement metrics, and rising confidence in freemium monetisation strategies. However, the maintained annual recurring revenue growth guidance indicates that Adobe continues to prioritise user base expansion over immediate revenue acceleration. Recommendation & Target Price Phillip Securities Research maintains a neutral recommendation on Adobe Inc. The target price has been raised to US$261 from the previous US$203, implying a 14.3 times fiscal 2026 price-to-earnings ratio, which remains below the stock's two-year average of 16 times. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Oracle Corp – Revenue Inflection as AI Monetisation Gains Traction
Brief Overview Oracle delivered a solid 1Q27 result that met expectations, with revenue rising 30% year-on-year, driven primarily by strong Cloud Infrastructure growth of 121%. The company expects group revenue to accelerate to 34% growth in FY27, compared to 16% in FY26, as cloud infrastructure deployment continues ramping up. Phillip Securities Research maintains a BUY recommendation whilst reducing the target price to US$225 from US$237. Investment Positives Accelerating Cloud Infrastructure Momentum Oracle Cloud Infrastructure (OCI) revenue growth surged to 121% year-on-year in 1Q27, accelerating from 93% in the previous quarter. The company's Stargate project is already generating revenue, with 6 of 8 buildings at the Abilene campus now operational, representing 618MW or 75% of planned capacity. This demonstrates that part of the OpenAI project has successfully transitioned from backlog into active revenue generation. The company's capacity deployment has accelerated significantly, delivering 850MW of compute capacity and over 300,000 GPUs in the quarter - nearly triple the prior quarter's deployment pace. This rapid scaling indicates Oracle's ability to capitalise on the strong AI demand environment. Strong Demand Visibility Through RPO Growth Oracle's remaining performance obligations (RPO) continue to grow robustly, increasing US$26 billion in quarter-on-quarter to US$664 billion, despite the accelerating OCI revenue conversion. This growth pattern indicates that demand remains well ahead of available capacity, positioning Oracle favourably for sustained growth. The company signed over US$30 billion of new AI contracts in Q1, supported by customer prepayments and alternative financing arrangements. Over the past three quarters, Oracle has secured US$105 billion in bookings under its new funding model, representing 16% of the total RPO. The RPO base is also becoming increasingly diversified, reducing concentration risk from OpenAI as the backlog expands. Challenges The report does not explicitly outline specific investment challenges or negative factors affecting Oracle's business prospects. Outlook Oracle expects significant revenue acceleration, with group revenue projected to grow 34% year-on-year in FY27, compared to 16% in FY26. Cloud Infrastructure revenue is forecast to surge 109% to US$38 billion, accounting for 42% of total group revenue. The majority of the US$300 billion OCI commitment is expected to ramp from 2027, whilst a potential IPO could strengthen funding capacity. Earnings are expected to be backloaded into a stronger second half of FY27 on data centre ramp-up. Recommendation & Target Price Phillip Securities Research maintains a BUY recommendation for Oracle Corp with a DCF target price of US$225, reduced from the previous target of US$237. The target price reduction reflects a higher share count by approximately 100 million shares following Oracle's recent At-the-Market equity issuance to fund its aggressive AI infrastructure and data centre expansion. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.
Sasseur REIT Shows Strong Growth Momentum Ahead of Anniversary Sales
Brief Overview Phillip Securities Research visited Sasseur REIT's outlet malls in Chongqing Liangjiang and Chongqing Bishan ahead of the Anniversary Sales. Both Chongqing outlets delivered steady sales growth in 2Q26, with the 1H26 Portfolio Sales reaching a record high since listing. The REIT's VIP membership base has continued expanding, exceeding 5.2 million members as of 1H26. Investment Positives Sasseur REIT demonstrates robust operational performance across its key properties. The Chongqing outlets maintained steady sales momentum, with Liangjiang achieving 3.7% year-on-year growth and Bishan recording 3.5% year-on-year growth in 2Q26. This contributed to the portfolio achieving record 1H26 sales, representing a 7.4% year-on-year increase and marking the highest first-half performance since the REIT's listing. The tenant composition presents a compelling diversification story across multiple retail categories. The portfolio features a well-balanced mix spanning domestic fashion brands including Bosideng, PoloWalk, and Biemlofen. International brands such as +39Space, Coach, and Navigare, and prominent sports brands including Nike, Adidas, and Fila. This diversification extends to tenant concentration risk management, with the top 10 tenants accounting for only 17% of gross revenue and no single tenant contributing more than 5% of total revenue. The VIP membership programme serves as a significant growth driver, with the member base expanding 17% year-on-year to exceed 5.2 million members as of 1H26. These VIP members contribute more than 60% of total sales, demonstrating their crucial role in driving portfolio performance. The growing membership base, supported by recurring promotional campaigns and member engagement initiatives, is expected to strengthen customer retention and support more resilient shoppers spending over time. Challenges The report does not explicitly outline specific investment challenges or risks facing Sasseur REIT. Outlook The research suggests a positive outlook supported by the expanding VIP membership base and ongoing promotional activities. The growing member engagement initiatives are expected to enhance customer retention and provide more resilient spending patterns, positioning the REIT for continued operational strength. Recommendation & Target Price The report does not specify Phillip Securities Research's investment recommendation or target price for Sasseur REIT. Frequently Asked Questions [market_journal_faq] This article has been auto-generated using PhillipGPT. It is based on a report by a Phillip Securities Research analyst. Disclaimer These commentaries are intended for general circulation and do not have regard to the specific investment objectives, financial situation and particular needs of any person. Accordingly, no warranty whatsoever is given and no liability whatsoever is accepted for any loss arising whether directly or indirectly as a result of any person acting based on this information. You should seek advice from a financial adviser regarding the suitability of any investment product(s) mentioned herein, taking into account your specific investment objectives, financial situation or particular needs, before making a commitment to invest in such products. Opinions expressed in these commentaries are subject to change without notice. Investments are subject to investment risks including the possible loss of the principal amount invested. The value of units in any fund and the income from them may fall as well as rise. Past performance figures as well as any projection or forecast used in these commentaries are not necessarily indicative of future or likely performance. Phillip Securities Pte Ltd (PSPL), its directors, connected persons or employees may from time to time have an interest in the financial instruments mentioned in these commentaries. The information contained in these commentaries has been obtained from public sources which PSPL has no reason to believe are unreliable and any analysis, forecasts, projections, expectations and opinions (collectively the “Research”) contained in these commentaries are based on such information and are expressions of belief only. PSPL has not verified this information and no representation or warranty, express or implied, is made that such information or Research is accurate, complete or verified or should be relied upon as such. Any such information or Research contained in these commentaries are subject to change, and PSPL shall not have any responsibility to maintain the information or Research made available or to supply any corrections, updates or releases in connection therewith. In no event will PSPL be liable for any special, indirect, incidental or consequential damages which may be incurred from the use of the information or Research made available, even if it has been advised of the possibility of such damages. The companies and their employees mentioned in these commentaries cannot be held liable for any errors, inaccuracies and/or omissions howsoever caused. Any opinion or advice herein is made on a general basis and is subject to change without notice. The information provided in these commentaries may contain optimistic statements regarding future events or future financial performance of countries, markets or companies. You must make your own financial assessment of the relevance, accuracy and adequacy of the information provided in these commentaries. Views and any strategies described in these commentaries may not be suitable for all investors. Opinions expressed herein may differ from the opinions expressed by other units of PSPL or its connected persons and associates. Any reference to or discussion of investment products or commodities in these commentaries is purely for illustrative purposes only and must not be construed as a recommendation, an offer or solicitation for the subscription, purchase or sale of the investment products or commodities mentioned. This advertisement has not been reviewed by the Monetary Authority of Singapore.